
Download Official Form IT649I (PDF)
Opens the official government PDF in a new tab
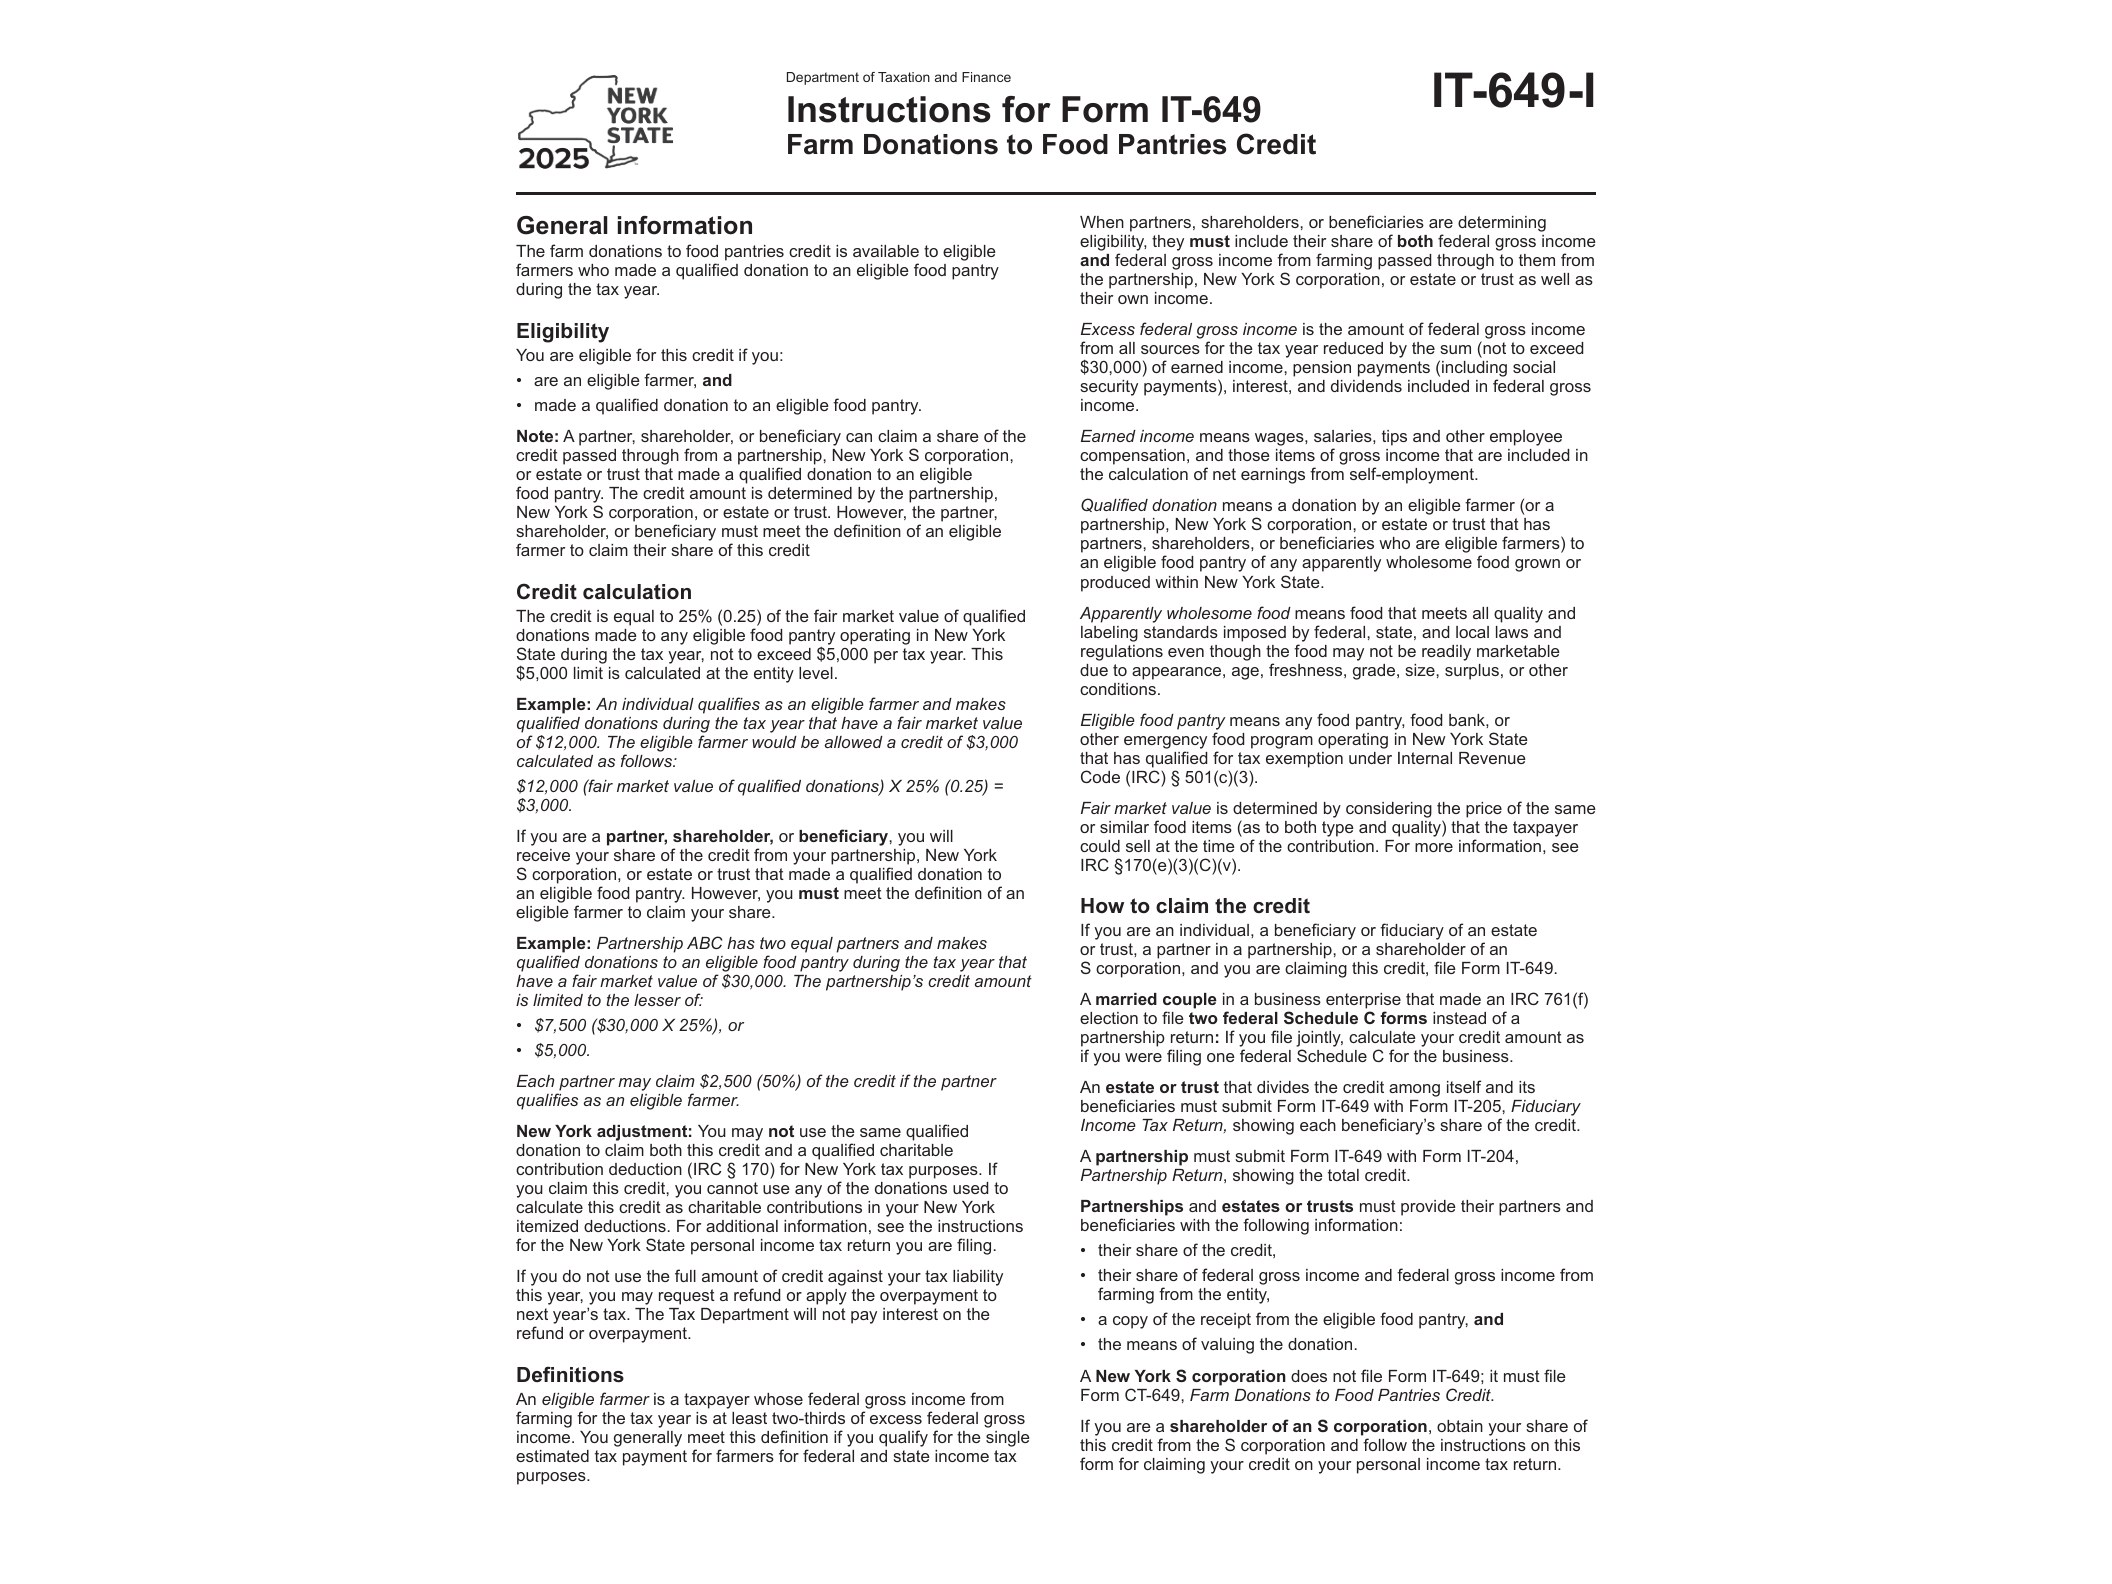
Form IT-649-I contains the official instructions from the New York State Department of Taxation and Finance for completing Form IT-649, the Farm Donations to Food Pantries Credit. This credit was created to encourage New York farmers to donate qualified food inventory to food pantries, food banks, and other emergency food programs rather than letting surplus crops go to waste. If you’re a farmer who made eligible donations during the 2025 tax year, this instructional booklet walks you through exactly how to calculate and claim the credit correctly.
The form itself is not fillable online. Taxpayers need to print the PDF and complete it by hand before attaching it to their New York State income tax return. The instructions booklet doesn’t replace Form IT-649 — it explains line by line how to fill it out, what documentation to keep, and how the credit interacts with other New York tax benefits.
Who Needs Form IT-649-I
This form is aimed specifically at eligible farmers — individuals, partnerships, or New York S corporations engaged in the business of farming — who donated qualified food inventory to a food pantry or emergency food program during the tax year. “Qualified food inventory” generally refers to food that meets quality and labeling standards under federal and state law but that the farmer chose to donate instead of selling.
If you didn’t farm in New York State or didn’t make any qualifying donations of food inventory during 2025, you don’t need this form. But if your farm business donated produce, dairy, meat, or other eligible food products to a qualifying nonprofit food pantry, this credit can offset a portion of that donation’s value against your state tax liability.
When to Use This Form
Form IT-649 is filed along with your New York State personal income tax return, or your corporation franchise tax return if you’re organized as a corporation, for the tax year in which the donations were made. Since the credit is nonrefundable but can be carried forward, farmers who don’t use the full credit amount in the year of donation may still benefit in future years — the instructions explain the specific carryforward rules and limitations.
The instructions also clarify how the credit is computed: generally, it’s a percentage of the fair market value of the donated food inventory, subject to certain caps. Because the calculation depends on accurate valuation of donated goods, farmers should keep detailed records — including donation receipts from the receiving food pantry, inventory logs, and any appraisal documentation — in case the Department of Taxation and Finance requests substantiation later.
How to Get and Complete the Form
The instructions and the form are distributed as a single PDF from the New York State Department of Taxation and Finance. Once downloaded, you’ll need a printer since there’s no digital fill-in option. After printing, complete each section by hand using black ink, following the line-by-line guidance in the instructions to determine your donation’s qualifying value and the resulting credit amount.
Farmers who also claim other New York State business credits should double check for any overlap or ordering rules. For example, businesses located in START-UP NY zones may want to review the Form IT-638 instructions for the START-UP NY Tax Elimination Credit to see how multiple credits interact on the same return. Those who previously claimed START-UP NY benefits but no longer qualify should also be aware of the Form IT-645 instructions for recapture of START-UP NY tax benefits, since recapture rules can affect overall tax liability calculations. If your farm business was also affected by a federally declared disaster, it may be worth reviewing the Form IT-651 instructions for the Recovery Tax Credit as well, since some farms qualify for more than one state credit in the same filing year.
Once Form IT-649 is completed and the credit amount is calculated, attach it to your applicable New York State tax return before the filing deadline. Keep a copy along with your donation records for at least three years in case of an audit or review request from the Tax Department.
Download Official Form IT649I (PDF)
Opens the official government PDF in a new tab