
Download Official Form ST141I (PDF)
Opens the official government PDF in a new tab
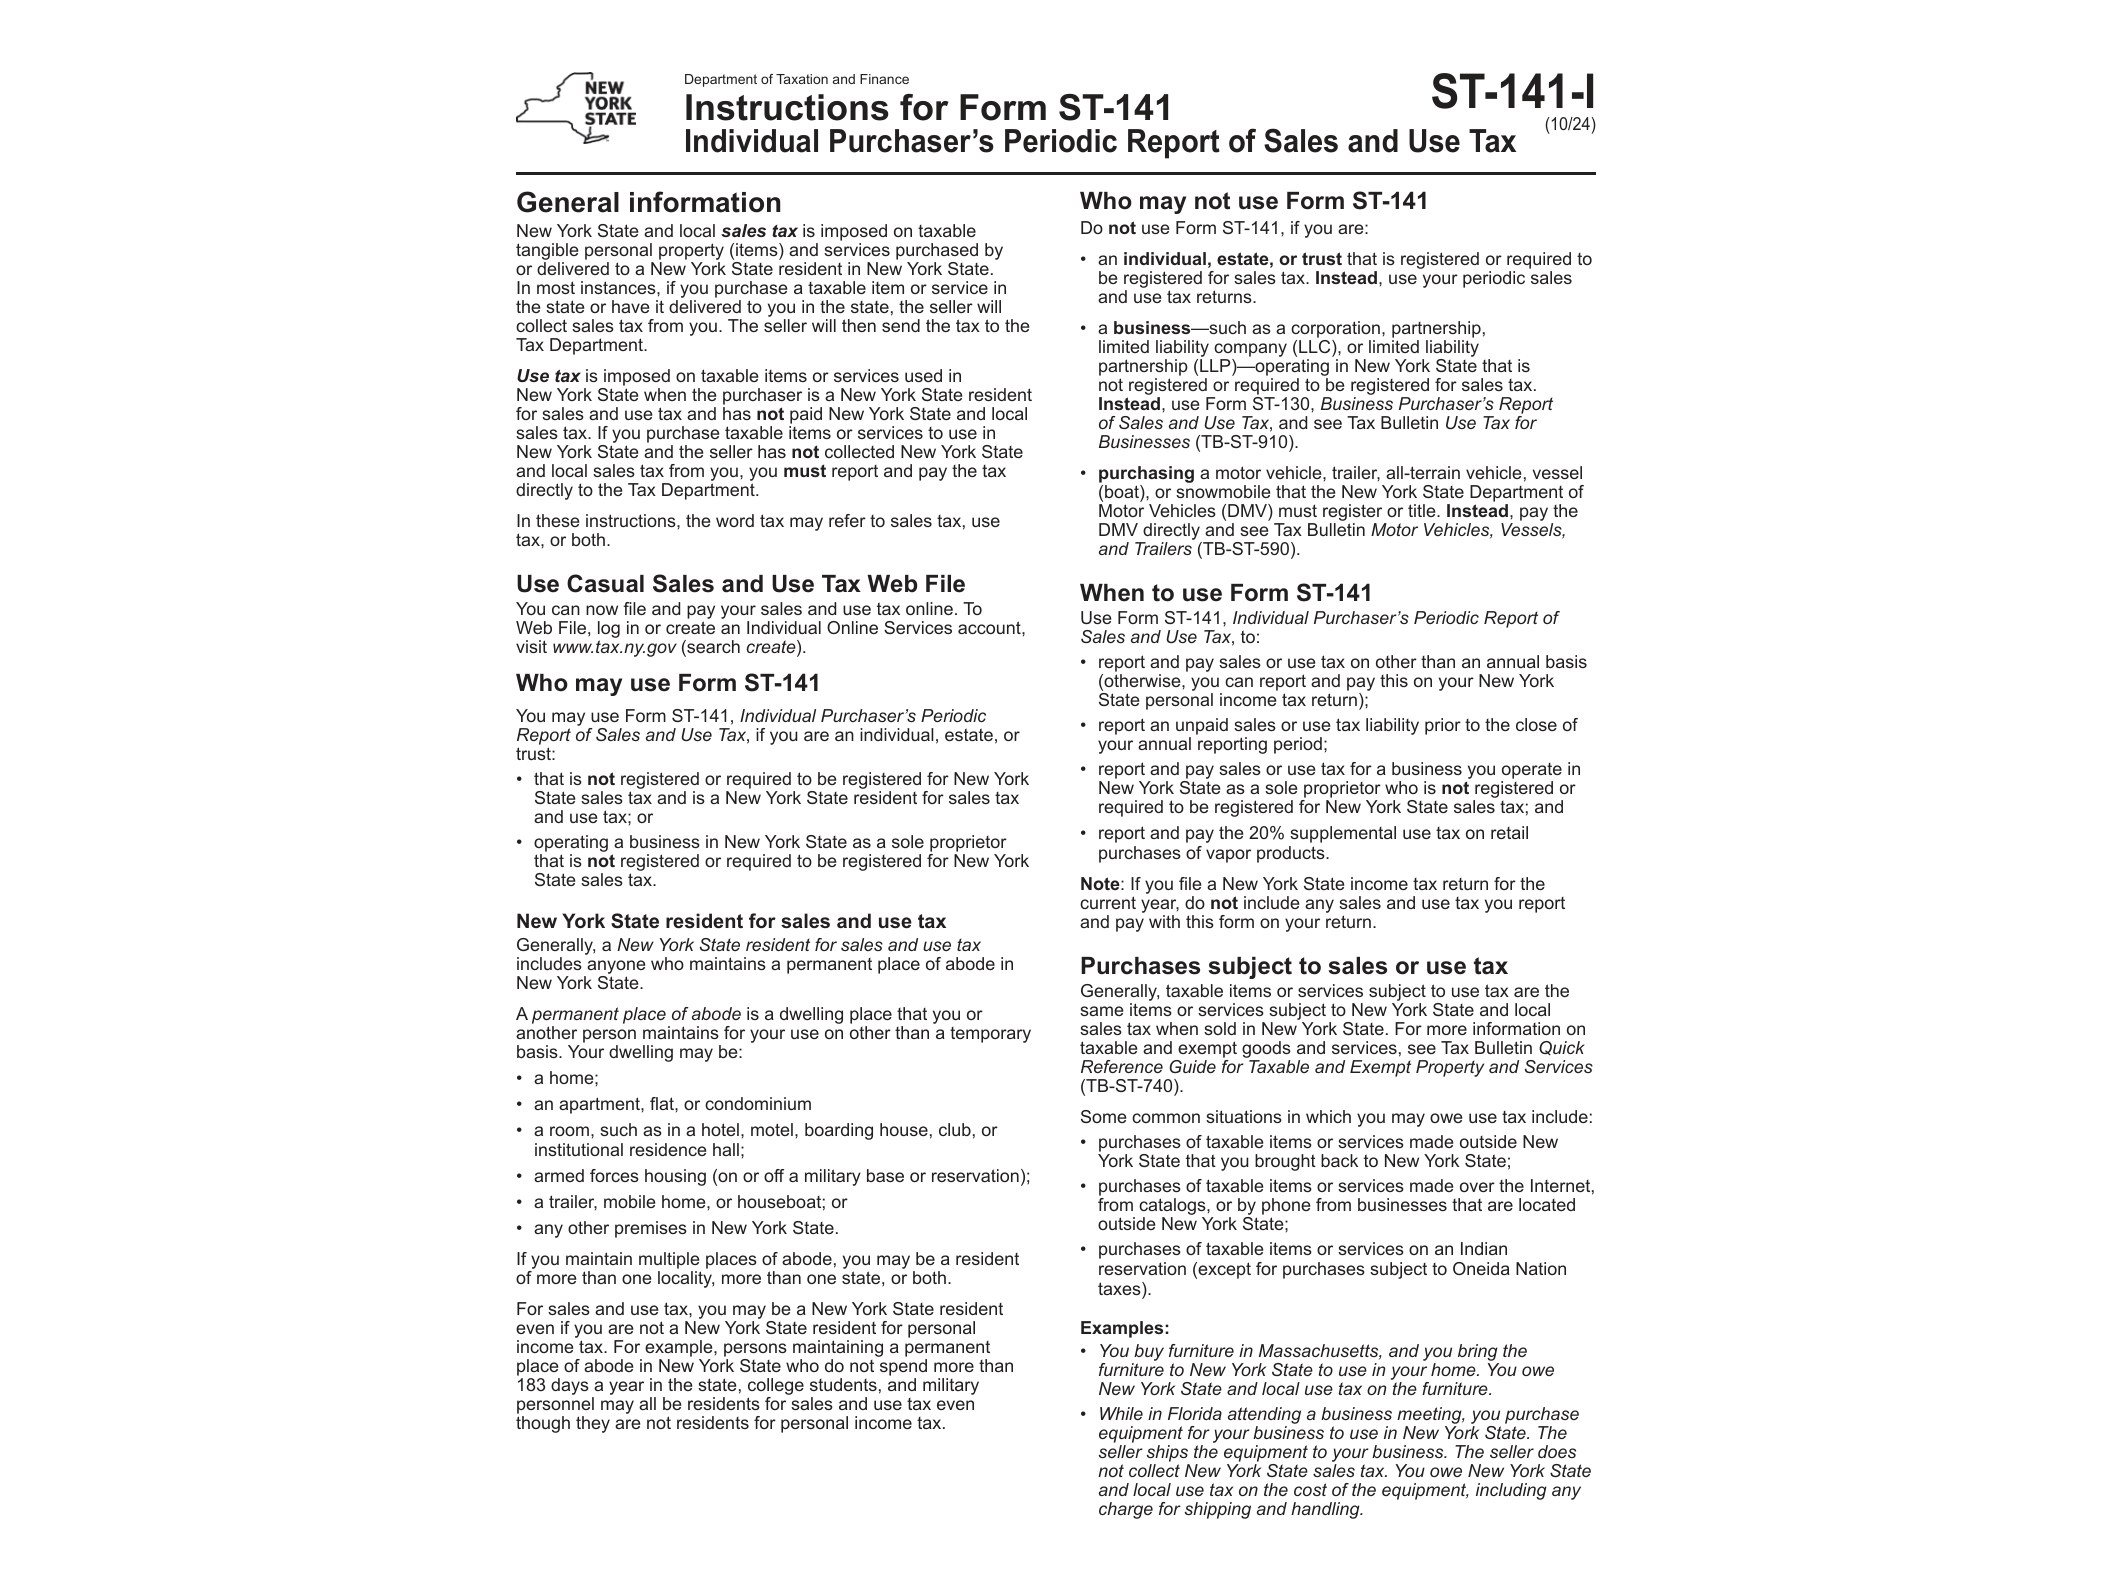
Form ST-141-I is the instruction packet that accompanies Form ST-141, Individual Purchaser’s Periodic Report of Sales and Use Tax, issued by the New York State Department of Taxation and Finance. This document walks taxpayers through how to complete and file ST-141 correctly, including who qualifies to use it, what deadlines apply, and how to calculate what’s owed. The version referenced here was revised in October 2024, so if you have an older copy sitting in a drawer, it’s worth downloading the current one before filing.
Form ST-141 itself is meant for individuals who make taxable purchases outside the ordinary retail channel and therefore haven’t paid sales tax at the point of sale. New York requires use tax to be paid directly to the state in these situations, and rather than reporting a single purchase on a one-off basis, some individuals are authorized by the Tax Department to report their taxable purchases on a recurring, periodic schedule. That’s where this form comes in. It’s typically used by people who have an ongoing pattern of purchases subject to use tax, rather than someone with a single isolated transaction.
The instructions clarify several practical points that trip people up. First, they explain the difference between sales tax and use tax for readers who aren’t familiar with the distinction: use tax applies when you buy taxable goods or services without paying New York sales tax, usually because the purchase was made out of state, over the internet, or from a seller not required to collect New York tax. If you later bring that item into New York for use, storage, or consumption, you generally owe use tax equal to what the sales tax would have been.
Second, the instructions detail the reporting periods available to individual purchasers who’ve been authorized to file periodically, along with the due dates tied to each period. Missing these dates can trigger penalties and interest, so the instructions spend time walking through how to calculate what’s due, including applicable local tax rates based on where the property or service was used, not necessarily where it was purchased.
Because Form ST-141 and its instructions are not fillable PDFs, you’ll need to print the form, complete it by hand, and mail it in according to the directions provided. There’s no digital submission option built into the form itself, so accuracy when writing in amounts, jurisdiction codes, and tax rates matters. The instructions include worksheets and rate tables to help individual filers get these numbers right the first time, since corrections after filing can be a hassle.
It’s also worth noting that this form is distinct from other New York sales tax filings aimed at businesses or specific industries. For example, operators of parking facilities in Manhattan have their own separate compliance requirements, detailed in Form TP-832. Sellers involved in casual sales, meanwhile, follow a different process entirely, outlined in the instructions for Form ST-131. And businesses operating as booking services have their own certificate requirements under Form ST-155. If your situation falls into one of these categories rather than individual periodic use tax reporting, you’ll want the form that actually matches your filing obligation.
Before filling out ST-141, read through the ST-141-I instructions fully at least once. They cover recordkeeping requirements, what documentation to keep in case of an audit, and how to handle situations where tax was partially paid to another state. Since the form must be filed by hand and mailed, give yourself enough lead time before the due date to avoid late submission, especially if you’re mailing from outside New York State.
Download Official Form ST141I (PDF)
Opens the official government PDF in a new tab