
Download Official Form CG15 (PDF)
Opens the official government PDF in a new tab
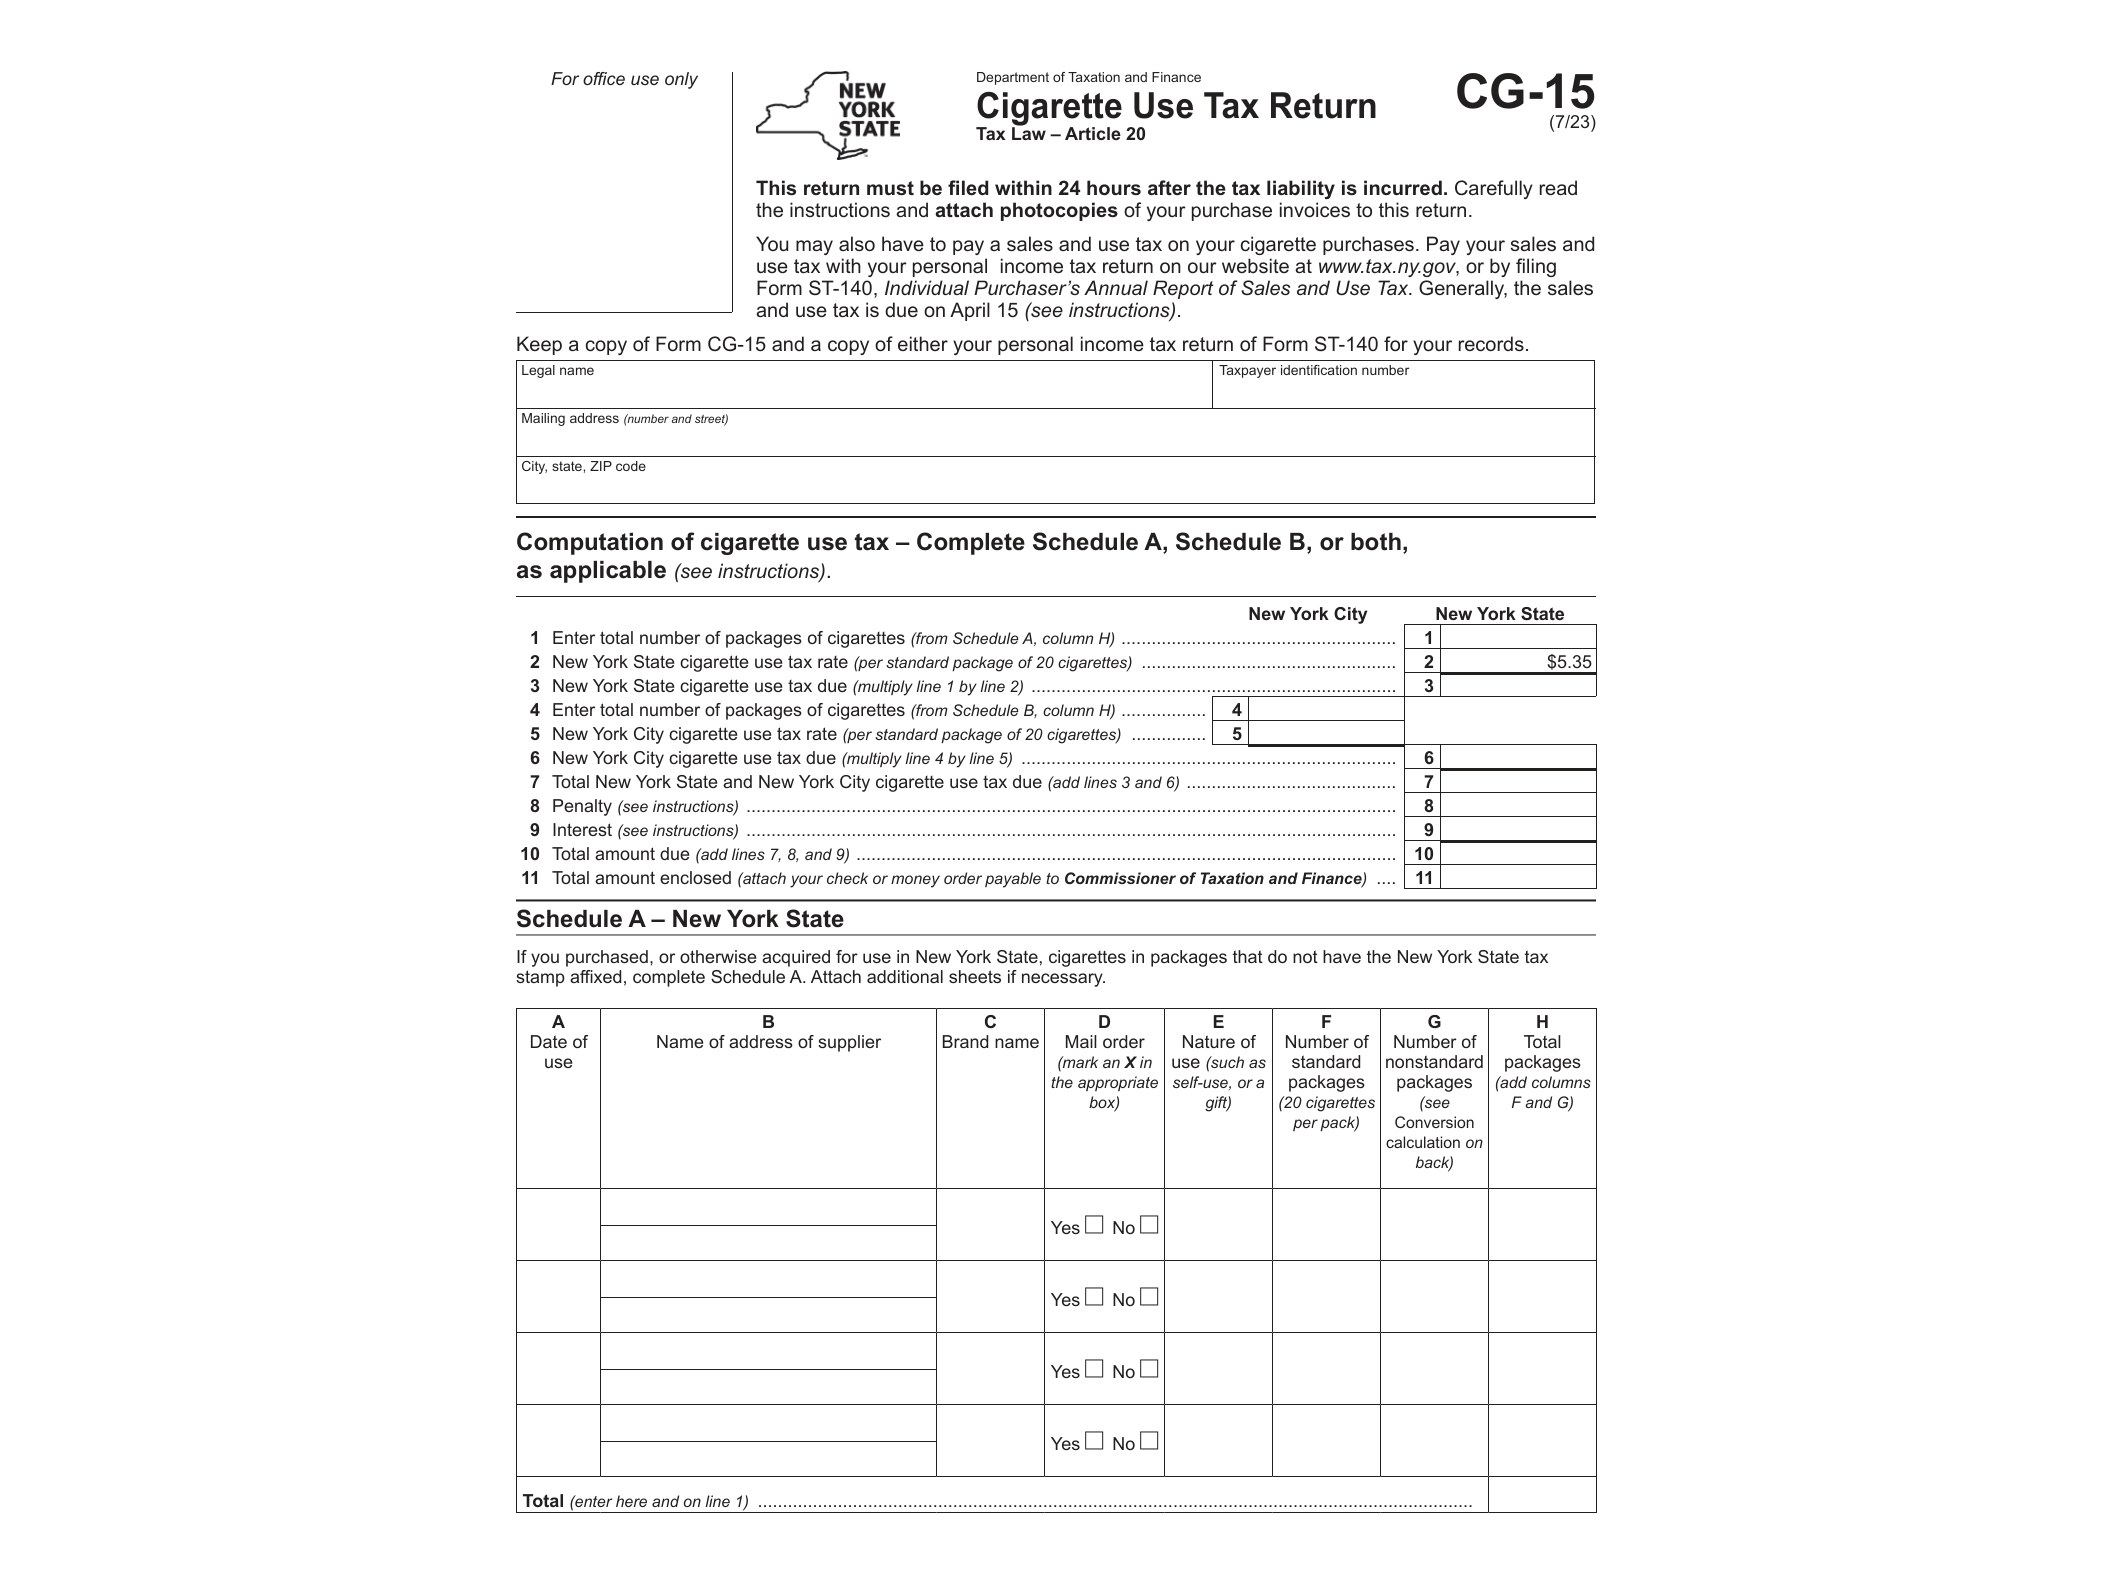
Form CG-15, Cigarette Use Tax Return, is issued by the New York State Department of Taxation and Finance for individuals and businesses that owe cigarette use tax on cigarettes brought into or possessed in New York State without the proper New York tax stamp. This tax exists separately from the standard cigarette excise tax paid by licensed agents and wholesalers, and it targets situations where cigarettes end up in New York without going through the normal stamped-cigarette distribution chain.
If you’re not sure how this form fits with the broader cigarette tax system in New York, it can help to also look at Form CG-30, which deals with Tobacco Master Settlement Agreement certification for cigarette manufacturers and importers. CG-15 and CG-30 serve different purposes, but both are part of how New York tracks and taxes cigarette products moving through the state.
Who Needs to File Form CG-15
This return applies to anyone who possesses unstamped or improperly stamped cigarettes in New York State for personal use or resale, outside of the licensed wholesale distribution system. Common situations include:
- Individuals who purchased cigarettes out of state or online and brought them into New York without paying the required tax
- Businesses or individuals who received cigarettes through mail order or shipment from another state
- Anyone holding cigarettes that don’t carry a valid New York tax stamp, regardless of how they were acquired
Licensed cigarette agents and wholesalers who already collect and remit tax through the standard stamping process generally don’t use this form for their regular inventory, since that tax is handled through a different mechanism at the distributor level.
When This Form Is Used
Form CG-15 is filed when cigarette use tax becomes due, which typically happens shortly after cigarettes are brought into New York or come into someone’s possession without the tax already paid through the stamp system. New York expects the tax to be reported and paid promptly rather than at some later annual filing deadline, since this isn’t an income tax return with a fixed yearly schedule. The return covers the specific transaction or quantity of cigarettes involved, so a filer may need to submit more than one CG-15 over time if multiple unstamped acquisitions occur.
The state uses this mechanism to close a gap that would otherwise let people avoid New York’s cigarette tax simply by purchasing cigarettes in a lower-tax jurisdiction and bringing them across state lines. New York has one of the highest cigarette tax rates in the country, so this use tax is a meaningful revenue and enforcement tool.
How to Get and Complete Form CG-15
The form is available directly from the New York State Department of Taxation and Finance website as a PDF. It’s worth noting that this particular version isn’t digitally fillable — there are no interactive form fields built into the PDF. That means you’ll need to download it, print a physical copy, and fill it out by hand using pen and legible handwriting.
Before filling it out, it’s a good idea to review Form CG-15-I, the official instructions that accompany this return. The instructions walk through exactly how to calculate the tax owed based on the number of cigarettes involved, what documentation to keep, and where to mail the completed form along with payment. Since the return isn’t something you can submit electronically, getting the calculations right on paper before mailing it in saves time and avoids processing delays.
Once completed, the form and any payment due are mailed to the address specified in the instructions. Keep a copy of the filled-out return and any supporting records, such as receipts showing where and when the cigarettes were purchased, in case the Department of Taxation and Finance has questions later.
For businesses dealing with broader tobacco compliance questions, particularly around manufacturer certification requirements, the instructions for Forms CG-30, CG-30.1, and CG-30.2 provide useful context, since New York’s tobacco tax framework involves several interconnected forms depending on whether you’re an individual consumer, a retailer, or a manufacturer.
Download Official Form CG15 (PDF)
Opens the official government PDF in a new tab