
Download Official Form DTF4157 (PDF)
Opens the official government PDF in a new tab
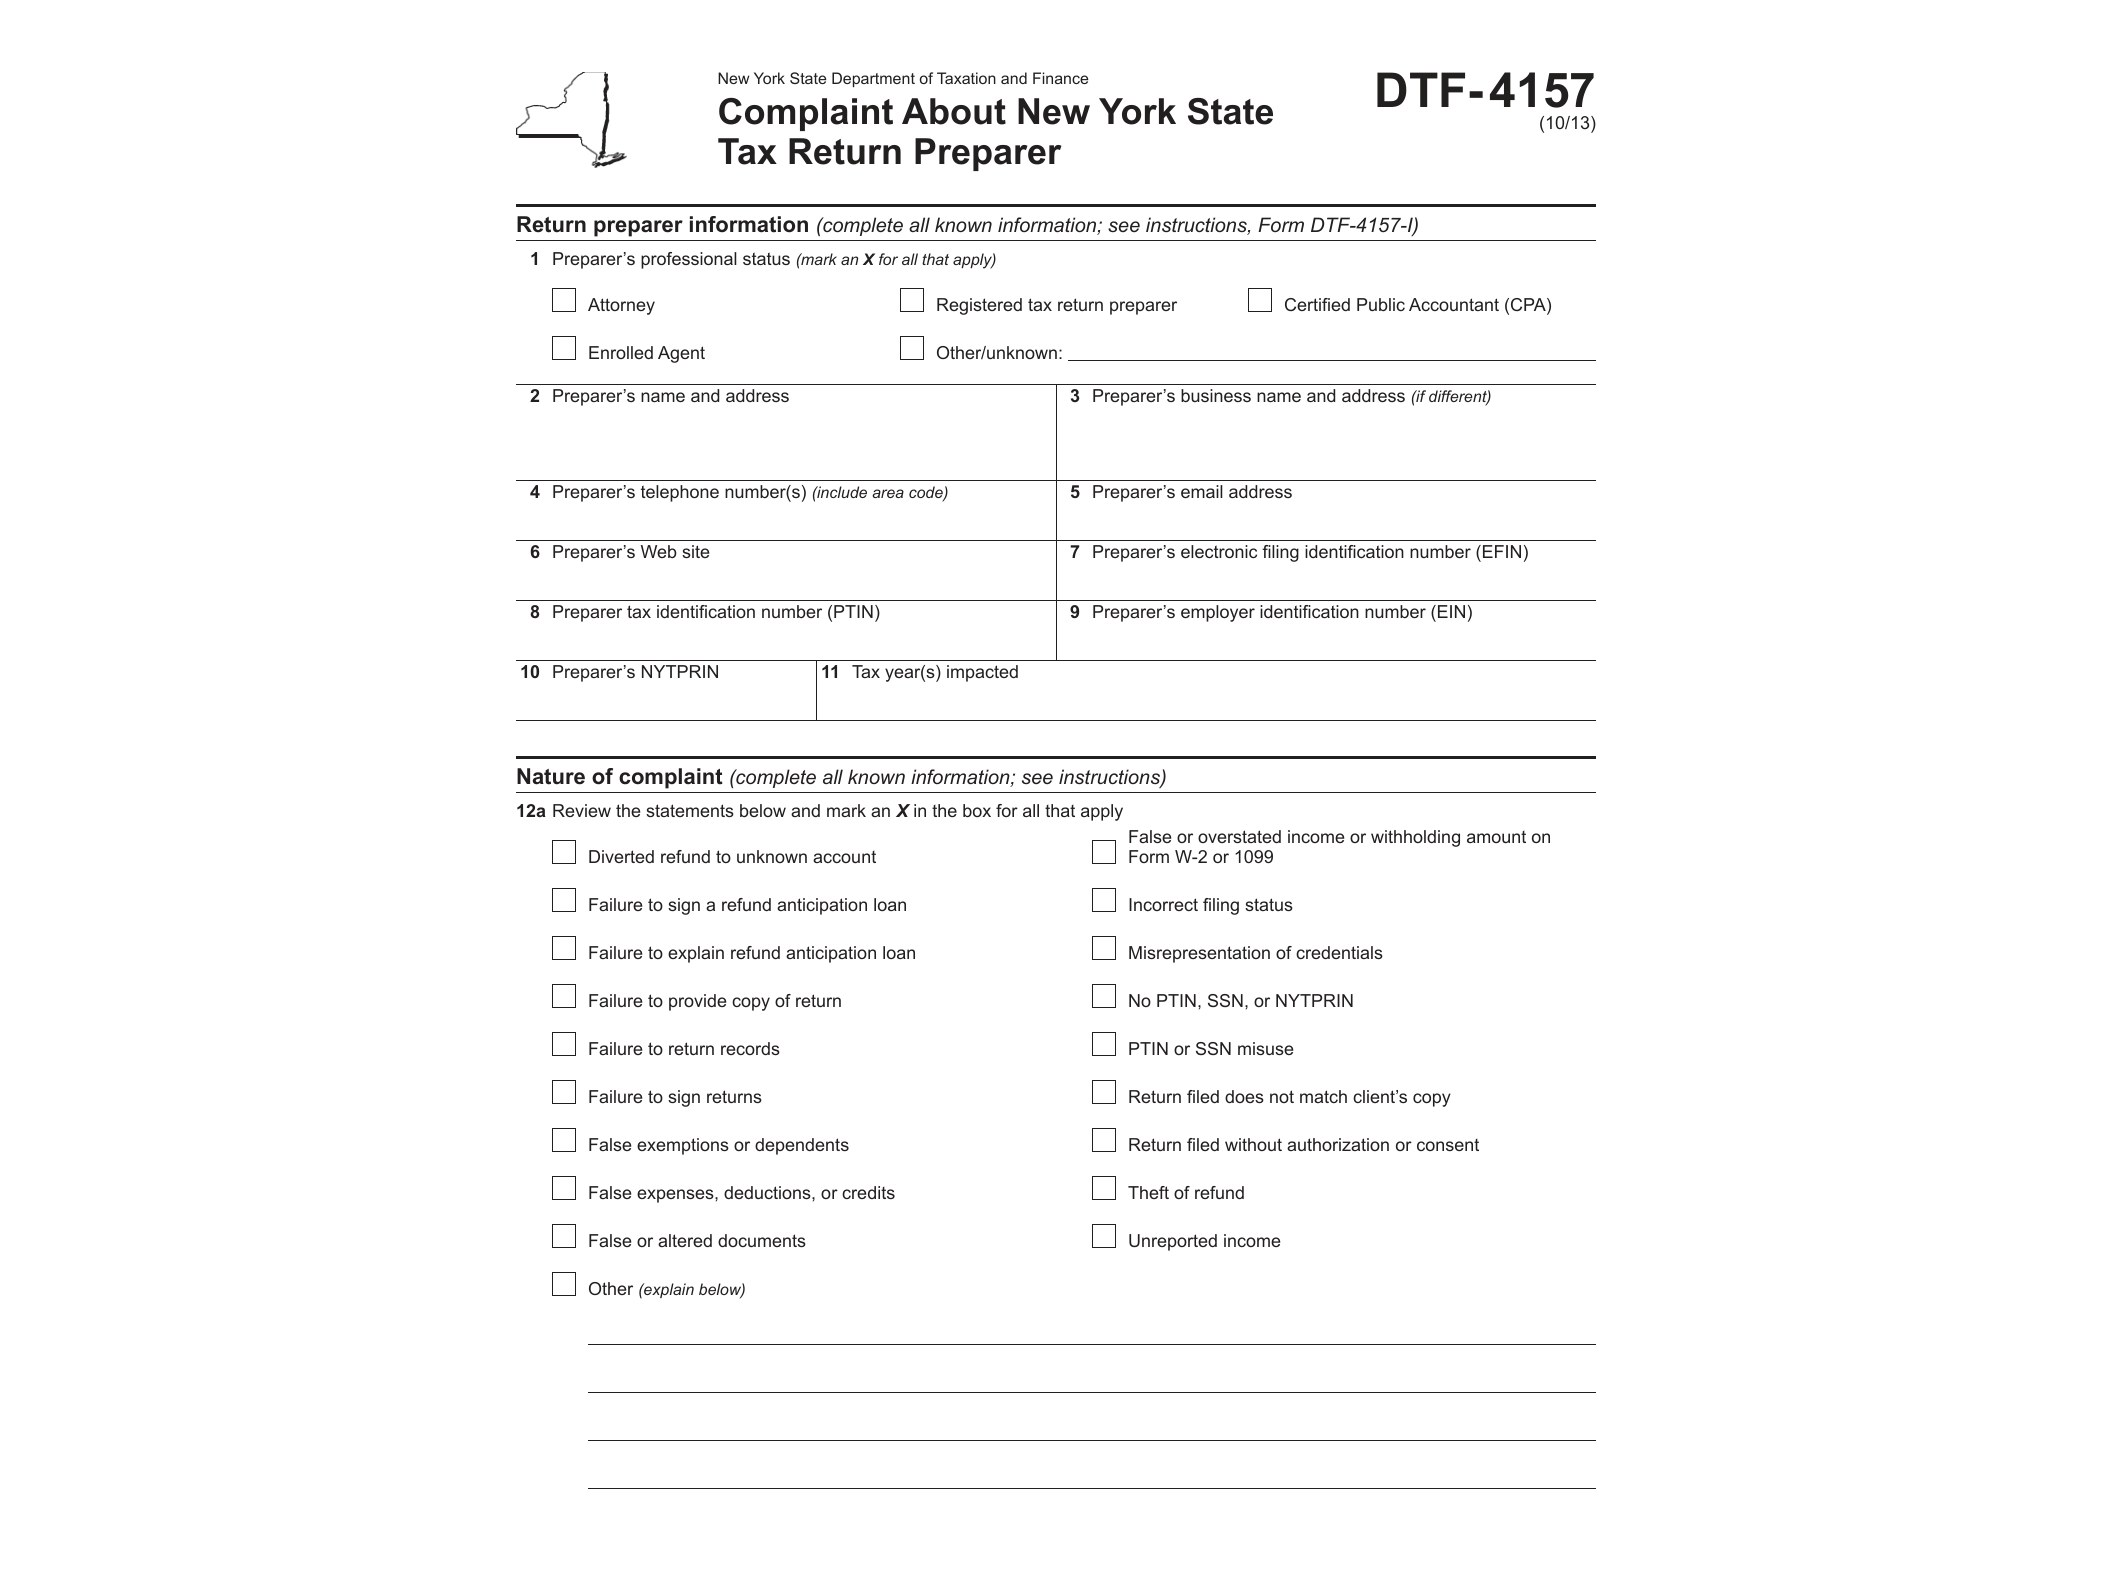
Form DTF-4157, Complaint About New York State Tax Return Preparer, is the official channel the New York State Department of Taxation and Finance provides for taxpayers who believe a paid tax preparer has acted improperly. If you paid someone to prepare your state tax return and suspect fraud, misrepresentation, overcharging, or other misconduct, this is the form the state expects you to use to put your concerns on record.
New York regulates paid tax return preparers under its own registration rules, separate from federal oversight. That means the state has a direct interest in knowing when a registered preparer isn’t following the rules, whether that involves inflating deductions without a client’s knowledge, failing to sign a return, charging fees based on the size of a refund, or simply disappearing after taking payment without filing anything. DTF-4157 gives the Department a formal, documented way to review these situations and take action when warranted.
Who Needs to File This Form
This form is meant for taxpayers, not for preparers reporting each other, although anyone with firsthand knowledge of misconduct can technically submit one. Common situations that lead people to file include discovering that a preparer submitted a return with false information, being charged fees that weren’t disclosed upfront, having a preparer refuse to provide a copy of the completed return, or noticing that a refund was redirected to an account that isn’t yours.
It’s also used when a preparer fails to sign the return as required or doesn’t include their Preparer Tax Identification Number, both of which are red flags under New York’s preparer regulations. If you’re not sure whether what happened rises to the level of a formal complaint, the form itself gives you space to describe the situation in detail, so the Department can make that determination.
When to Use DTF-4157
There’s no strict deadline tied to a tax year for filing this complaint, but it makes sense to submit it as soon as you become aware of the issue, especially if there’s an ongoing pattern that could affect other taxpayers. If the preparer’s conduct also involves a return still under audit or one that hasn’t been filed correctly, filing the complaint promptly can help the Department connect the dots faster.
Keep in mind this form addresses the preparer’s conduct, not disputes over your own tax liability. If you’re contesting an assessment or a notice you received from the state, that’s handled through a different process entirely. DTF-4157 is specifically about the person or firm who prepared your return, not about the substance of a tax bill.
How to Get and Complete the Form
Form DTF-4157 is available directly from the Department’s website as a PDF. It does not have fillable digital fields, so you’ll need to print it out and complete it by hand. Once filled in, it’s mailed to the address listed in the form’s instructions rather than submitted online.
When completing it, be as specific as possible. Include the preparer’s name, business name if applicable, address, and PTIN or other identifying information if you have it. Describe the dates of service, what was promised, what actually happened, and any documentation you can attach, such as copies of the return, receipts, or correspondence. The more concrete detail you provide, the easier it is for the Department to investigate.
This kind of consumer-protection paperwork sits alongside other specialized state tax forms that don’t get much everyday attention but matter a great deal to the people who need them. If you’ve dealt with unusual state tax filings before, you might also find it useful to look at how other niche forms work, like the Form CT-33-D filing for premiums paid to unauthorized insurers, or how compliance certifications function for regulated industries such as the Form CG-213-I certification of compliance. Reviewing how New York structures its reporting requirements across different areas, including something like the Form CG-5 nonresident agent cigarette tax report, gives a broader sense of how the Department expects documentation and disclosure to work across the board.
Once your complaint is submitted, the Department reviews it as part of its oversight of registered tax preparers. While they won’t necessarily update you on every step of an investigation, filing DTF-4157 creates an official record that can support enforcement action against preparers who repeatedly cause problems for New York taxpayers.
Download Official Form DTF4157 (PDF)
Opens the official government PDF in a new tab