
Download Official Form FT1007 (PDF)
Opens the official government PDF in a new tab
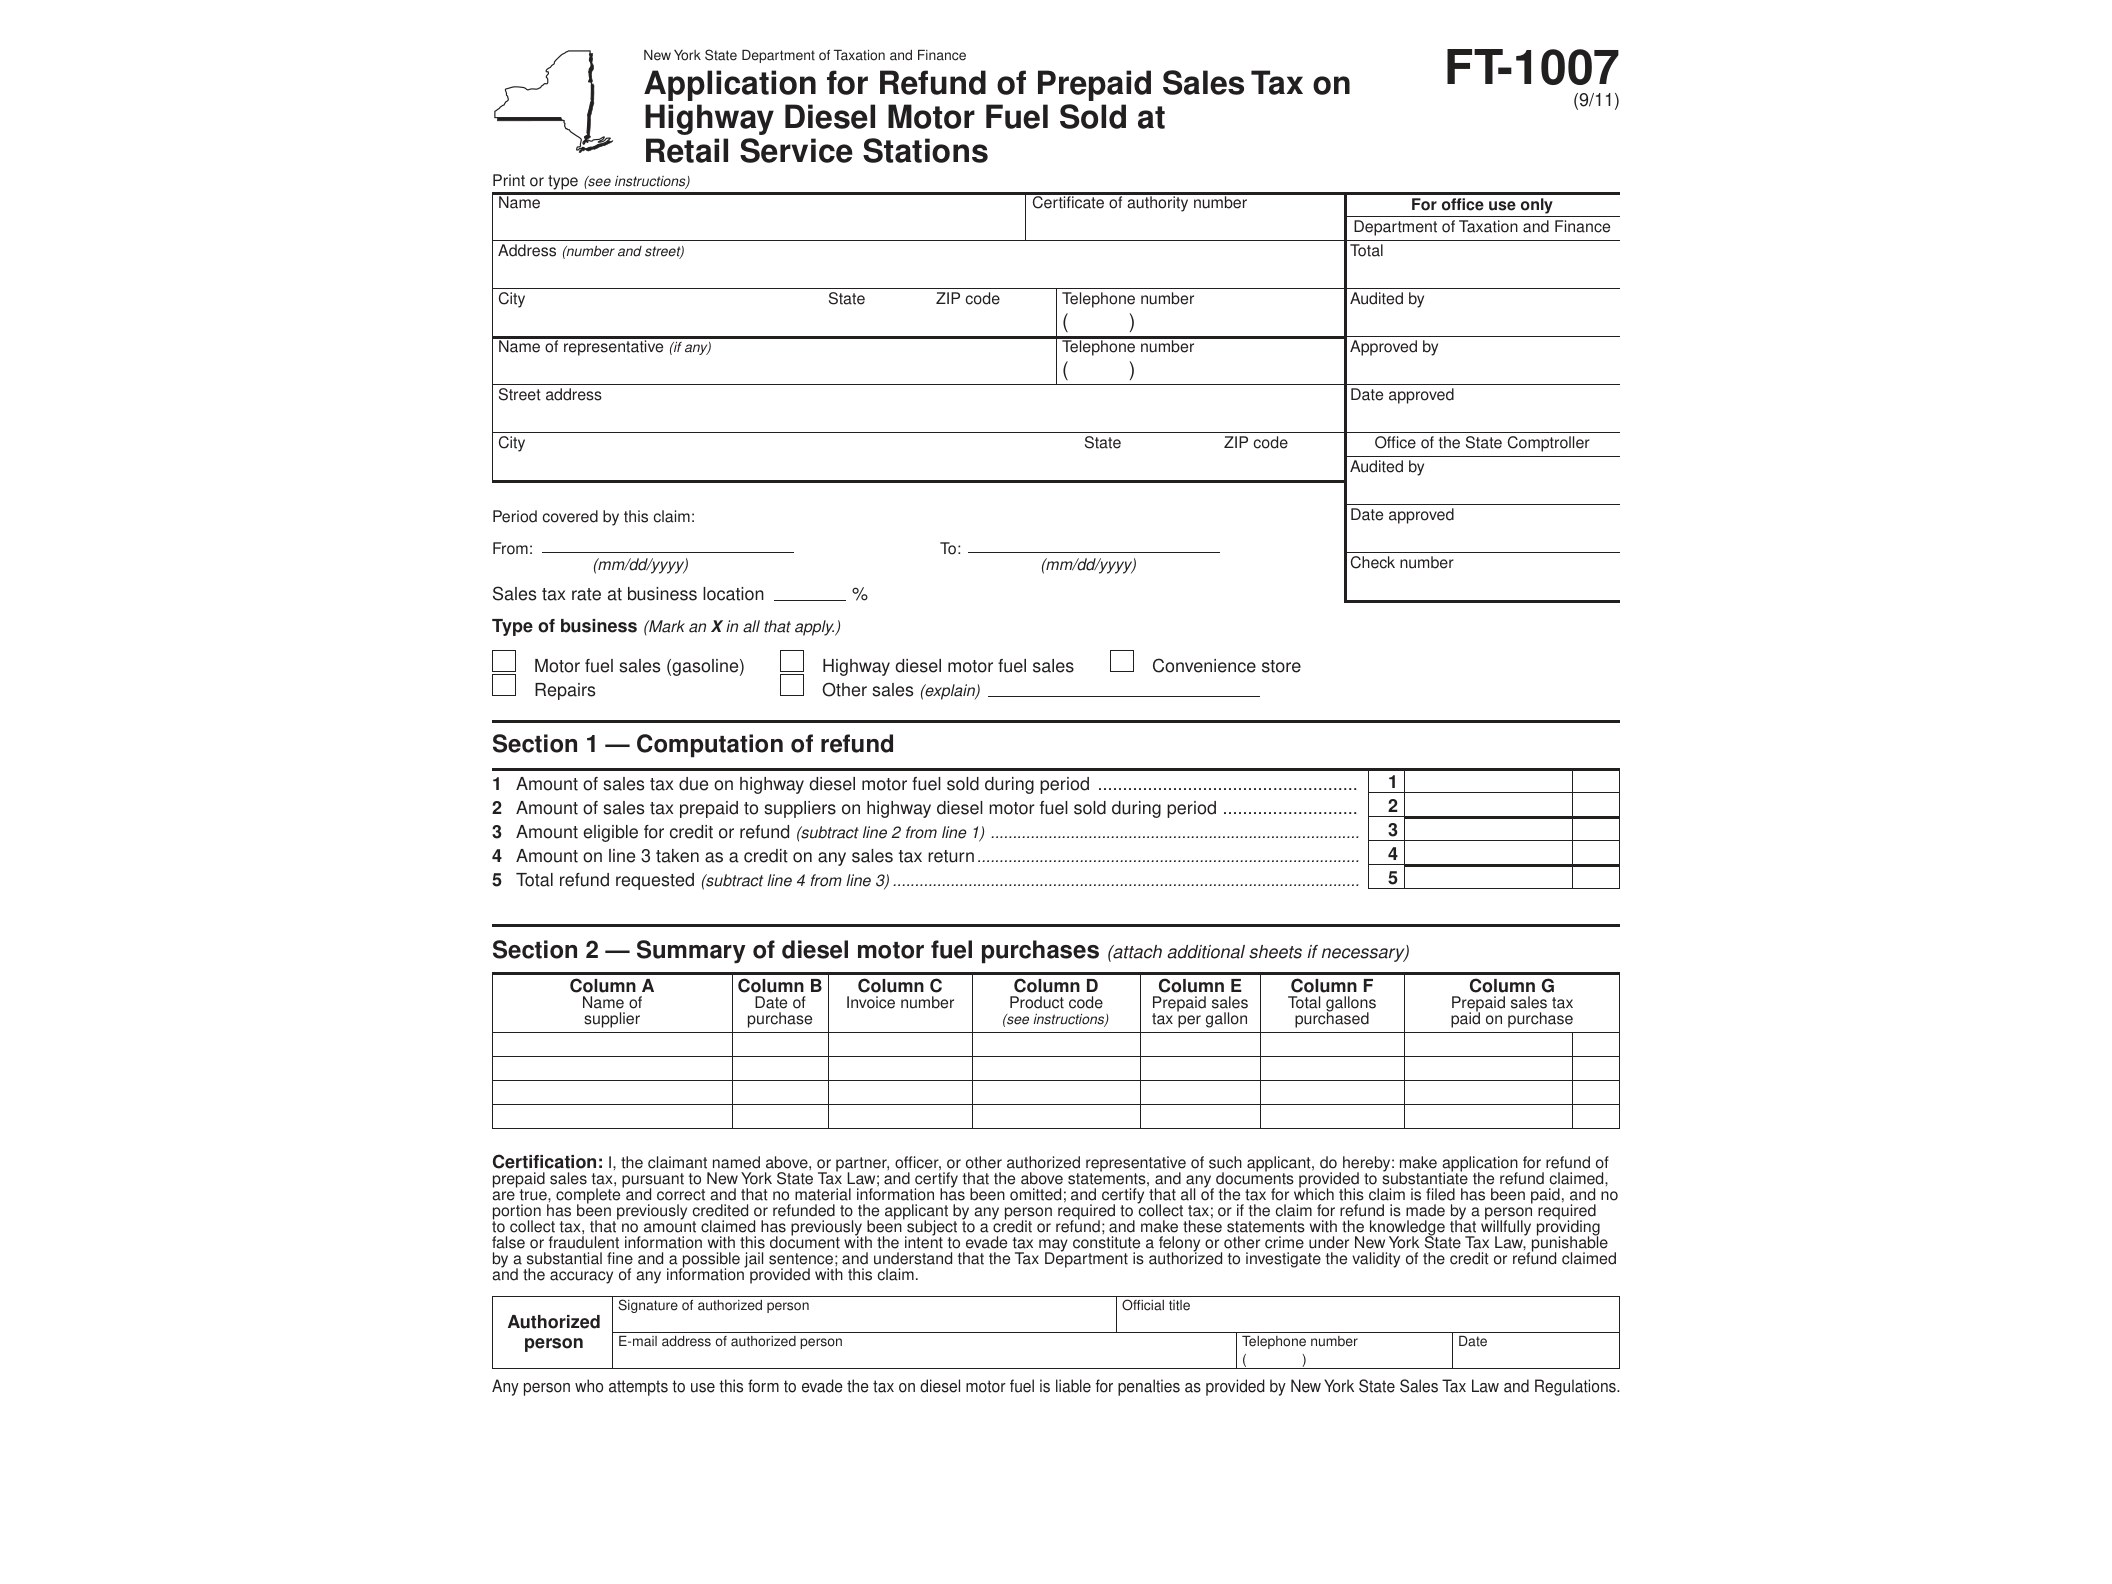
Form FT-1007, issued by the New York State Department of Taxation and Finance, lets eligible retailers of highway diesel motor fuel apply for a refund of prepaid sales tax. This applies specifically to diesel sold at retail service stations, where sales tax is collected upfront at the distributor or wholesaler level before the fuel ever reaches the pump. When the actual retail sale generates less tax liability than what was prepaid, or when certain sales qualify for exemption, the retailer is owed money back from the state.
The prepaid sales tax system for diesel motor fuel works differently than standard retail sales tax collection. Distributors add a prepaid sales tax amount to the price of diesel sold to retailers, and that cost gets passed down the chain. Retail station operators then collect sales tax from customers at the pump. In many cases, the amount collected at retail doesn’t match what was prepaid further up the supply chain, creating either a shortfall or an overpayment. Form FT-1007 exists to reconcile that overpayment and get the excess back into the hands of the business that paid it.
Who Needs to File This Form
This form is intended for operators of retail service stations that sell highway diesel motor fuel in New York State. If your station paid prepaid sales tax on diesel inventory but your actual retail sales didn’t generate enough tax to offset that prepayment, you’re a candidate for this refund. It’s not a form for individual consumers or for businesses buying diesel for their own fleet use — it’s strictly for the retail sellers caught in the middle of the prepaid tax structure.
Gas station owners, convenience store operators with fuel pumps, and truck stop operators who sell diesel at retail are the typical filers. If your station deals in both gasoline and diesel, you’ll want to confirm which fuel types qualify under this specific form versus other refund mechanisms, since New York separates refund procedures by fuel category and sales channel.
When to Use Form FT-1007
You’d file this form after completing a sales period and determining that your prepaid tax liability exceeded your actual collected sales tax on diesel sold at retail. This isn’t something filed in anticipation of a sale — it’s a retrospective claim based on actual transaction records. Retailers typically review their fuel purchase invoices (which show the prepaid tax amount) against their retail sales records to calculate the refund owed.
Timing matters here. New York imposes statute of limitations rules on refund claims, so retailers shouldn’t let too much time pass between the sales period in question and filing the form. Keeping organized records of fuel purchases and retail sales throughout the year makes this calculation far easier when it’s time to file.
How to Complete and Submit the Form
Form FT-1007 is a paper-only form — there’s no fillable digital version available through the Tax Department’s website. You’ll need to download the PDF, print it, and fill it out by hand. The form asks for identifying information about your business, details on the fuel purchases subject to prepaid tax, and a calculation of the refund amount based on your retail sales figures.
Supporting documentation is typically required alongside the form, including purchase invoices showing the prepaid tax charged by your distributor. Without this backup, the Tax Department has no way to verify your claimed refund amount, so it’s worth organizing these records before you sit down to complete the form.
Retailers dealing with petroleum products more broadly might also want to look at Form FT-500, which covers refund applications for sales tax paid on other petroleum products beyond highway diesel. If your business also handles transactions involving nonresident customers or tax-exempt buyers, forms like DTF-820 for nonresidency certification may come into play depending on your customer base. Stations that occasionally serve diplomatic personnel should also be aware of Form DTF-950, which handles sales tax exemptions for those specific transactions.
Once completed, mail the form along with required documentation to the address specified in the form instructions. Processing times vary, so retailers should factor this into their cash flow planning rather than expecting an immediate turnaround.
Download Official Form FT1007 (PDF)
Opens the official government PDF in a new tab