
Download Official Form ST112 (PDF)
Opens the official government PDF in a new tab
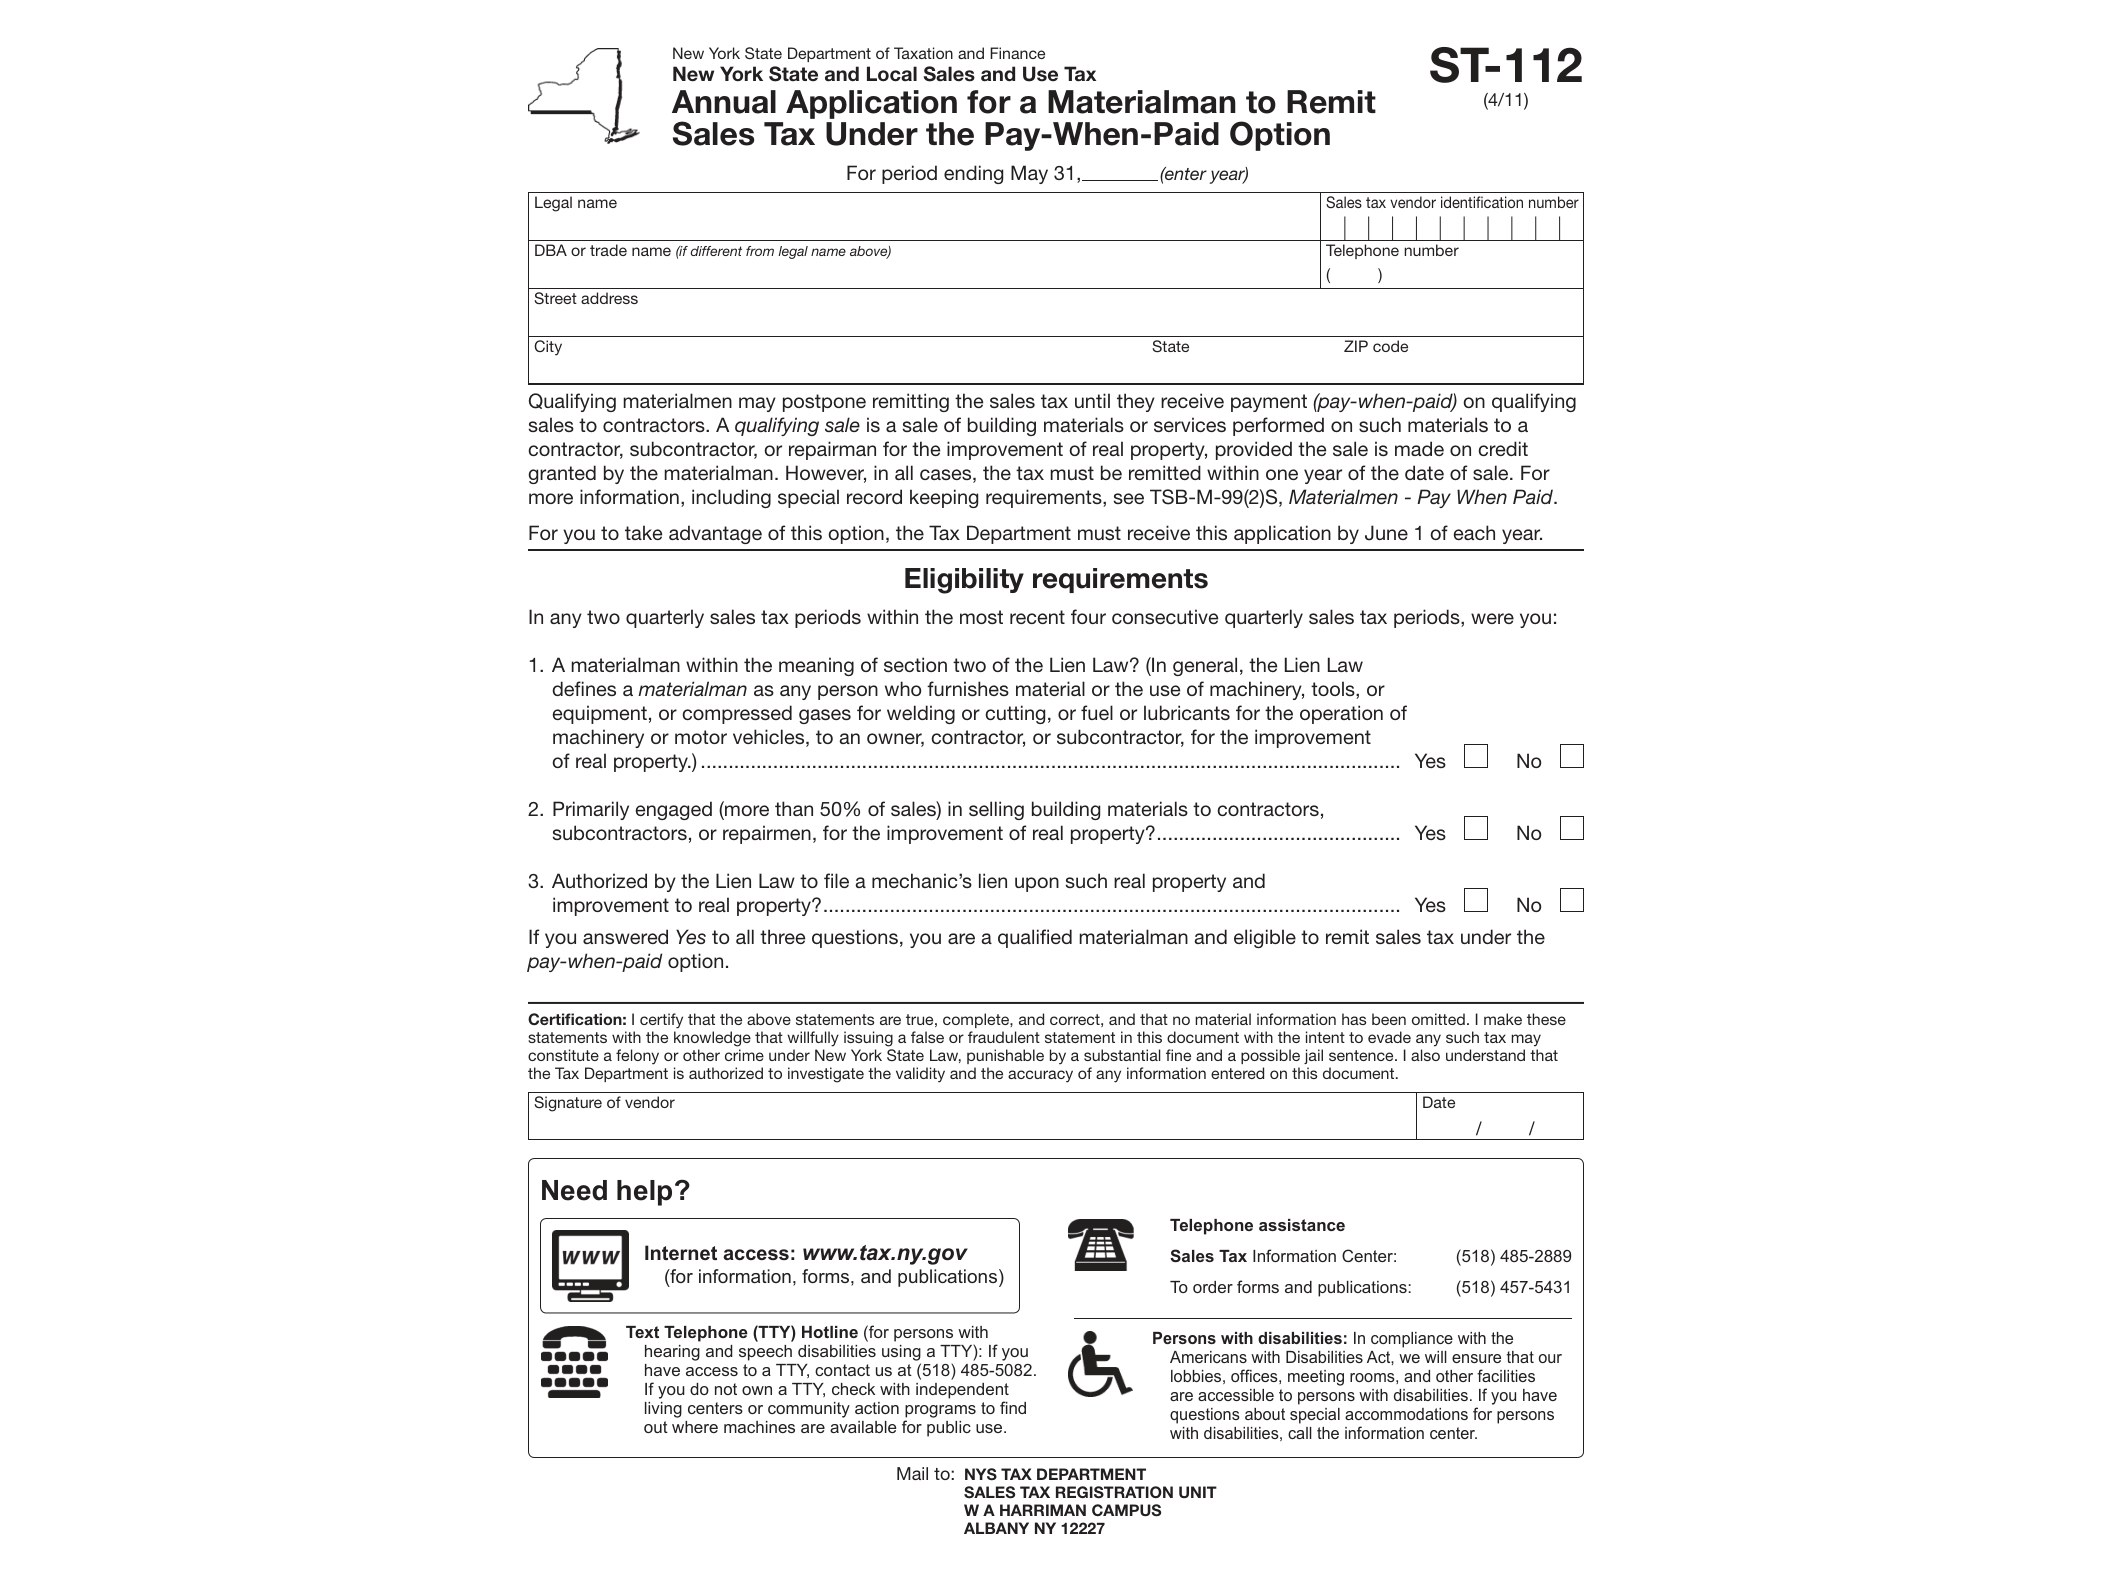
Form ST-112 is an annual application used by businesses classified as “materialmen” in New York State who want to remit sales tax using the pay-when-paid option instead of the standard accrual method. It’s issued by the New York State Department of Taxation and Finance and must be filed each year to maintain this special remittance privilege.
Under normal rules, a vendor who sells taxable goods or services generally has to remit sales tax to the state based on when the sale occurs, regardless of whether the customer has actually paid. For materialmen who sell building materials to contractors on credit terms — where payment can take months to come in — this creates a cash flow problem. The pay-when-paid option solves that by allowing the materialman to remit sales tax only after receiving payment from the customer, rather than fronting the tax before the money comes in.
Who Needs This Form
This form is specifically for materialmen — businesses that sell building materials, supplies, or equipment to contractors, subcontractors, or builders, typically on open account or credit terms. If your business regularly extends credit to customers in the construction trade and sales tax remittance timing creates a financial strain, this option is designed for you.
Not every vendor qualifies. The Department of Taxation and Finance evaluates applicants based on their business model, the nature of their sales, and whether they meet the statutory definition of a materialman under New York tax law. Simply selling building supplies isn’t automatically enough; the applicant needs to demonstrate that the pay-when-paid structure reflects how their actual sales and collections work.
When the Form Is Used
Form ST-112 is not a one-time filing. Because it’s an annual application, materialmen who already use the pay-when-paid option must reapply each year to continue the privilege. The state reviews these applications periodically to confirm that the business still meets the eligibility requirements and that the option isn’t being misused to simply delay tax payments without a legitimate credit-sale business reason.
Businesses that are applying for the first time should expect to provide detailed information about their sales practices, typical payment terms with customers, and how they currently handle sales tax collection and remittance. The state uses this information to confirm that pay-when-paid treatment is appropriate for the specific business.
How to Get and Complete the Form
Form ST-112 is available directly from the New York State Department of Taxation and Finance as a PDF. It’s important to note that this particular form is not fillable online — there are no digital form fields. You’ll need to download the PDF, print it, and fill it out by hand before submitting it according to the instructions on the form.
When completing it, have your business identification details ready, including your sales tax Certificate of Authority number, a description of your business operations, and documentation or explanation of your typical credit sales arrangements with contractor customers. Since the application is reviewed annually, keep a copy of what you submit along with any correspondence from the Department in case questions arise about your continued eligibility in future years.
Materialmen dealing with sales tax on building materials sometimes also handle related fuel or exemption paperwork depending on the nature of their inventory and customers. For example, businesses involved in fuel sales might also need to review Form FT-950 for prepaid sales tax refunds on motor fuel, or Form ST-101.10 covering sales and use tax on qualified motor fuel. And if your business occasionally deals with specialized exemption certificates, it’s worth comparing how those differ from an annual application like ST-112 by looking at something like Form ST-126, the exemption certificate for racehorse purchases, which follows a very different filing logic since it applies to a single transaction rather than an ongoing remittance method.
Because approval for pay-when-paid treatment affects how and when your business remits sales tax throughout the year, it’s worth submitting Form ST-112 well ahead of your renewal deadline rather than waiting until the last minute. Gaps in approval could force a temporary switch back to standard remittance timing, which defeats the purpose of applying for this option in the first place.
Download Official Form ST112 (PDF)
Opens the official government PDF in a new tab