
Download Official Form FT950 (PDF)
Opens the official government PDF in a new tab
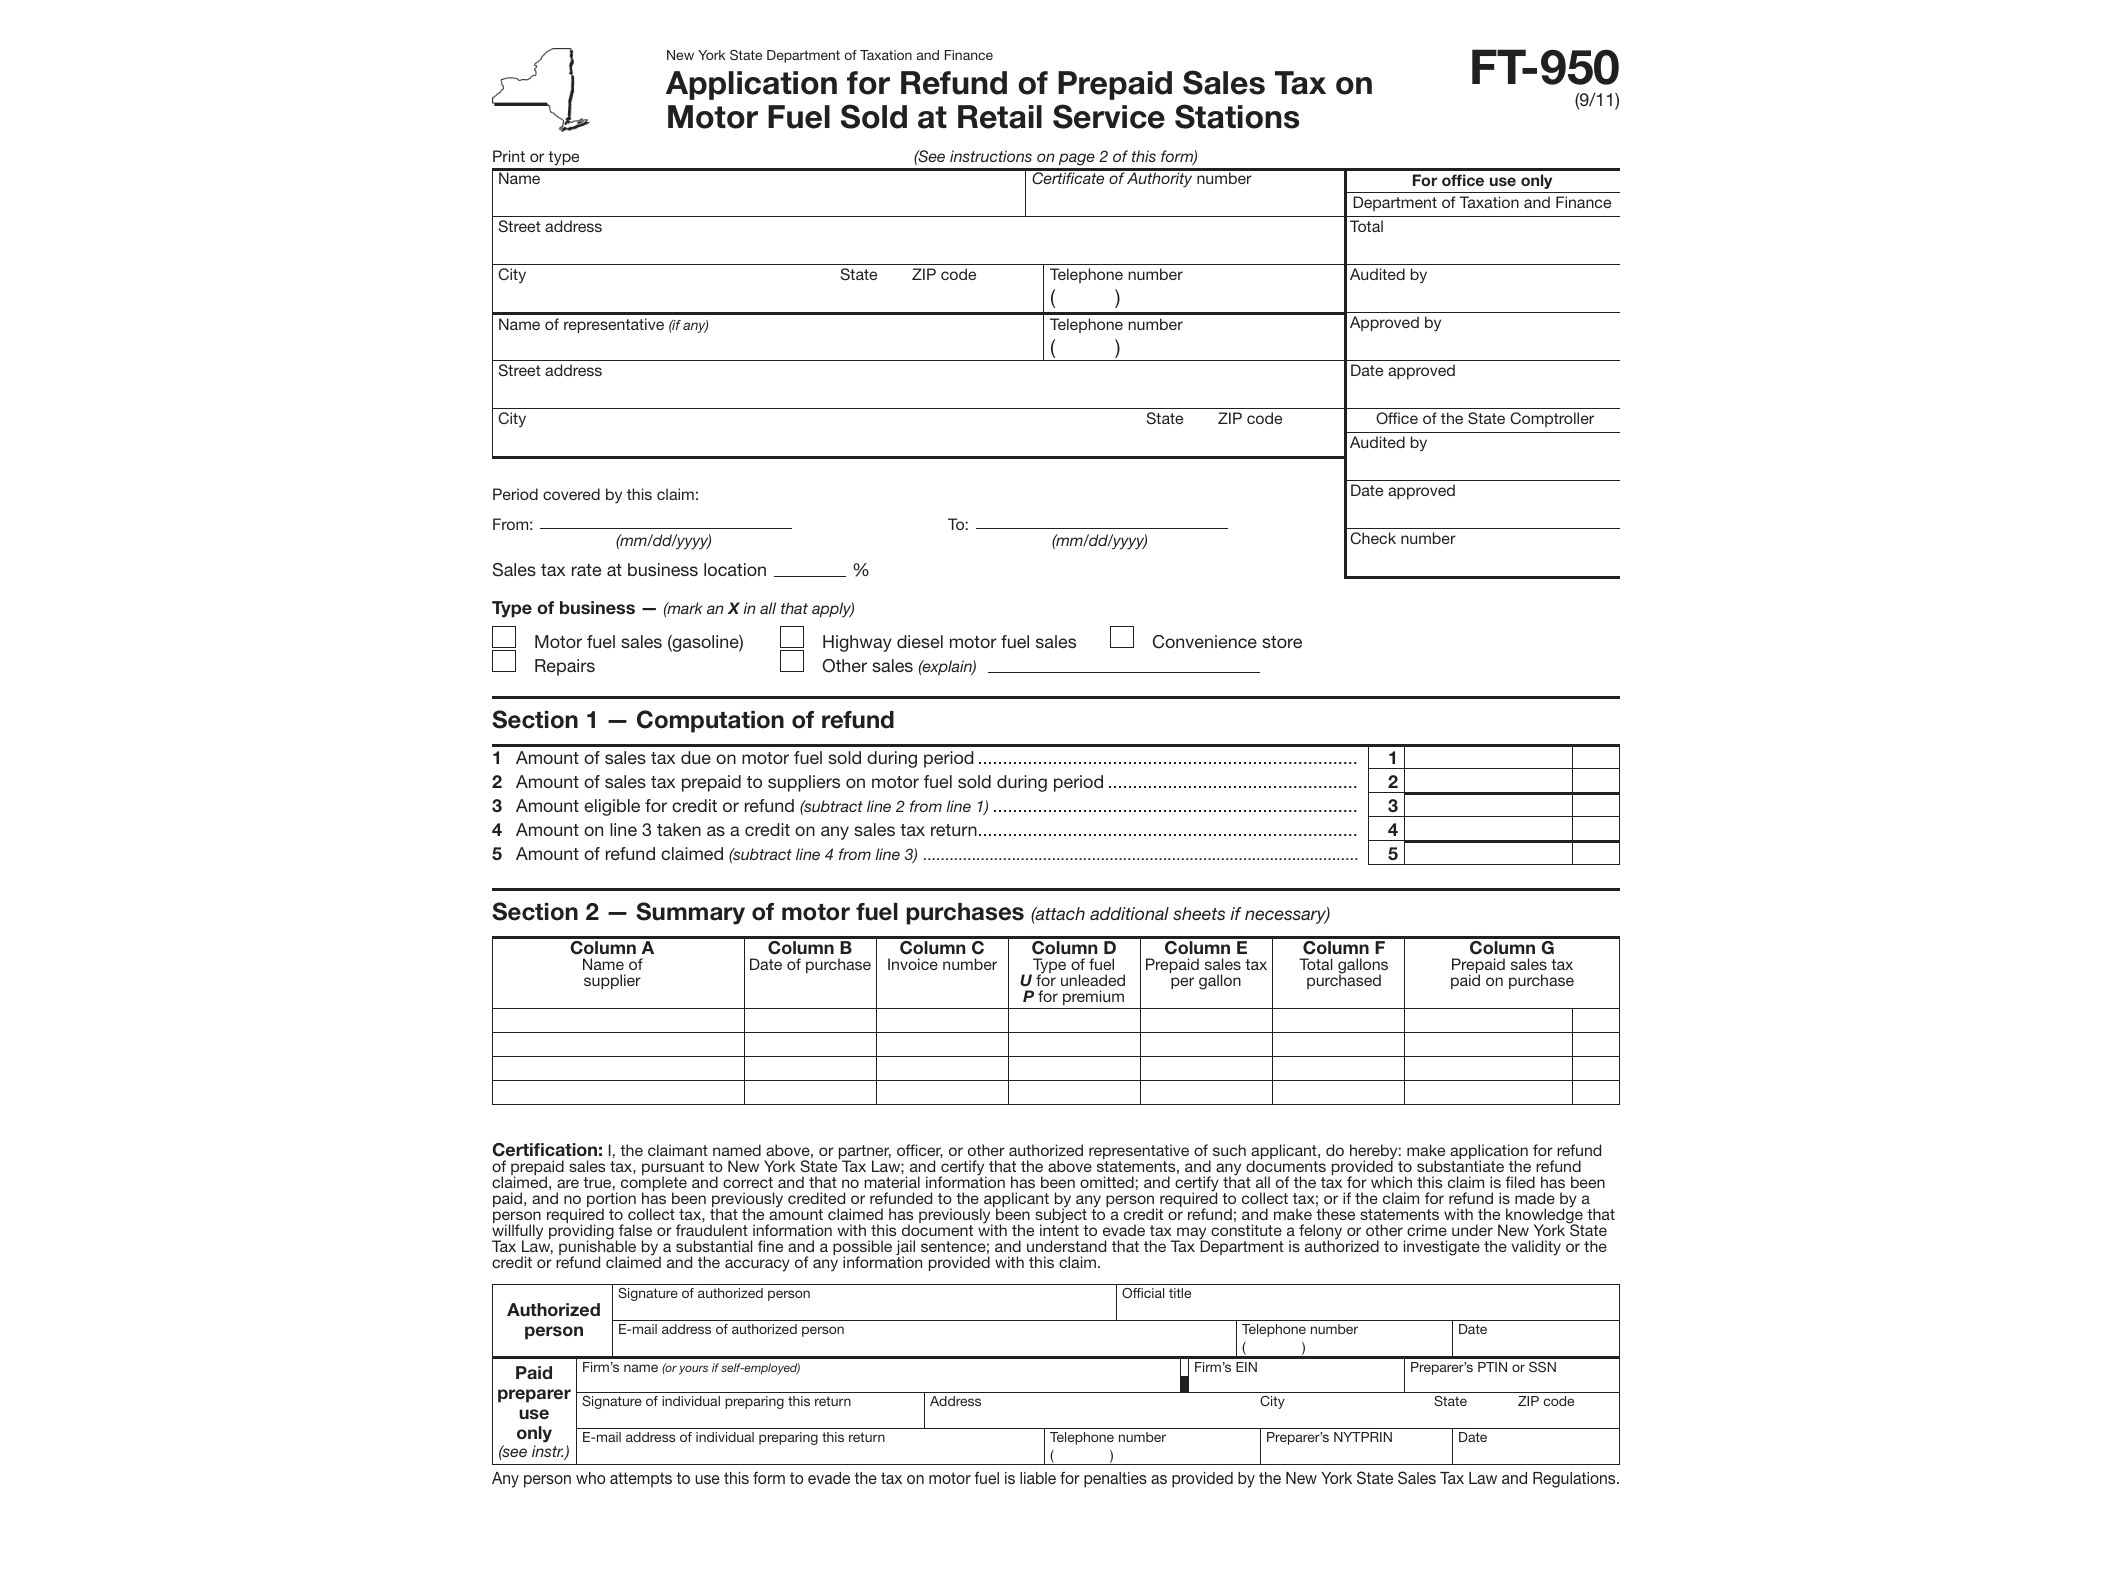
Form FT-950, issued by the New York State Department of Taxation and Finance, lets retail service stations apply for a refund of prepaid sales tax on motor fuel. Retailers in New York often pay sales tax on fuel in advance, based on the prepaid sales tax rate set by the state, before the fuel is actually sold at the pump. When the amount prepaid ends up higher than the tax actually due on retail sales, this form is how a station owner recovers the difference.
This situation comes up more often than people expect. Fuel prices fluctuate, prepaid tax rates are updated periodically, and a station’s actual retail sales volume or pricing may not line up perfectly with the assumptions baked into the prepaid rate. Form FT-950 exists specifically to correct that mismatch and put money back in the hands of the business that overpaid.
Who Needs to File Form FT-950
This form is for owners and operators of retail service stations in New York State who sell motor fuel directly to consumers and who prepaid sales tax on that fuel through their fuel supplier. If you’re a distributor rather than a retailer, this particular refund mechanism doesn’t apply to you in the same way — your reporting obligations run through different filings, such as the ones covered in Form ST-101.10 for qualified motor fuel and highway diesel sales tax.
Retail service station operators who also file Form FT-943, the quarterly inventory report, will recognize a lot of overlap here. Both forms deal with reconciling what actually moved through the pumps against what was reported or taxed upfront. Keeping accurate inventory records through FT-943 makes completing FT-950 considerably easier, since you’ll already have the sales and gallonage figures you need to support your refund claim.
When to Use This Form
You file Form FT-950 after you’ve identified a gap between the prepaid sales tax your supplier charged you and the sales tax you actually collected and owed on retail sales. This typically gets caught during a sales tax filing period review or during an internal reconciliation of fuel purchases versus fuel sold. There’s no monthly automatic process for this — it’s an application you submit when you’ve done the math and determined a refund is owed to you.
Timing matters. The Tax Department enforces a statute of limitations on refund claims, so station owners shouldn’t let these applications pile up. If you suspect you’ve overpaid prepaid sales tax over several periods, it’s worth working through the numbers promptly rather than waiting until year-end.
How to Fill Out and Submit Form FT-950
Form FT-950 is not a fillable PDF. You’ll need to download it, print it, and complete it by hand in ink. Before you start, gather your fuel purchase invoices showing the prepaid sales tax charged, your retail sales records for the period in question, and your sales tax filings covering that same time frame. The form will ask you to calculate the difference between tax prepaid and tax actually due, so having clean documentation on hand prevents errors that could delay processing.
Fill in your business identification details, the period covered by the refund request, and the supporting calculations exactly as instructed on the form. Attach any required documentation — copies of invoices or supplier statements are usually necessary to substantiate the prepaid amounts. Double-check your math before mailing it in, since discrepancies between your reported figures and your supporting documents are one of the most common reasons refund applications get sent back for correction.
Once completed, mail the form to the address specified in the instructions on the PDF itself. Keep a copy of everything you submit, including the supporting invoices, in case the Department has follow-up questions or requests additional verification. Station owners who also handle exemption paperwork for specialty sales, like the documentation required under Form ST-126 for racehorse purchase exemptions, know that New York tax paperwork rewards precision — the same holds true here with FT-950.
Download Official Form FT950 (PDF)
Opens the official government PDF in a new tab