
Download Official Form AU631 (PDF)
Opens the official government PDF in a new tab
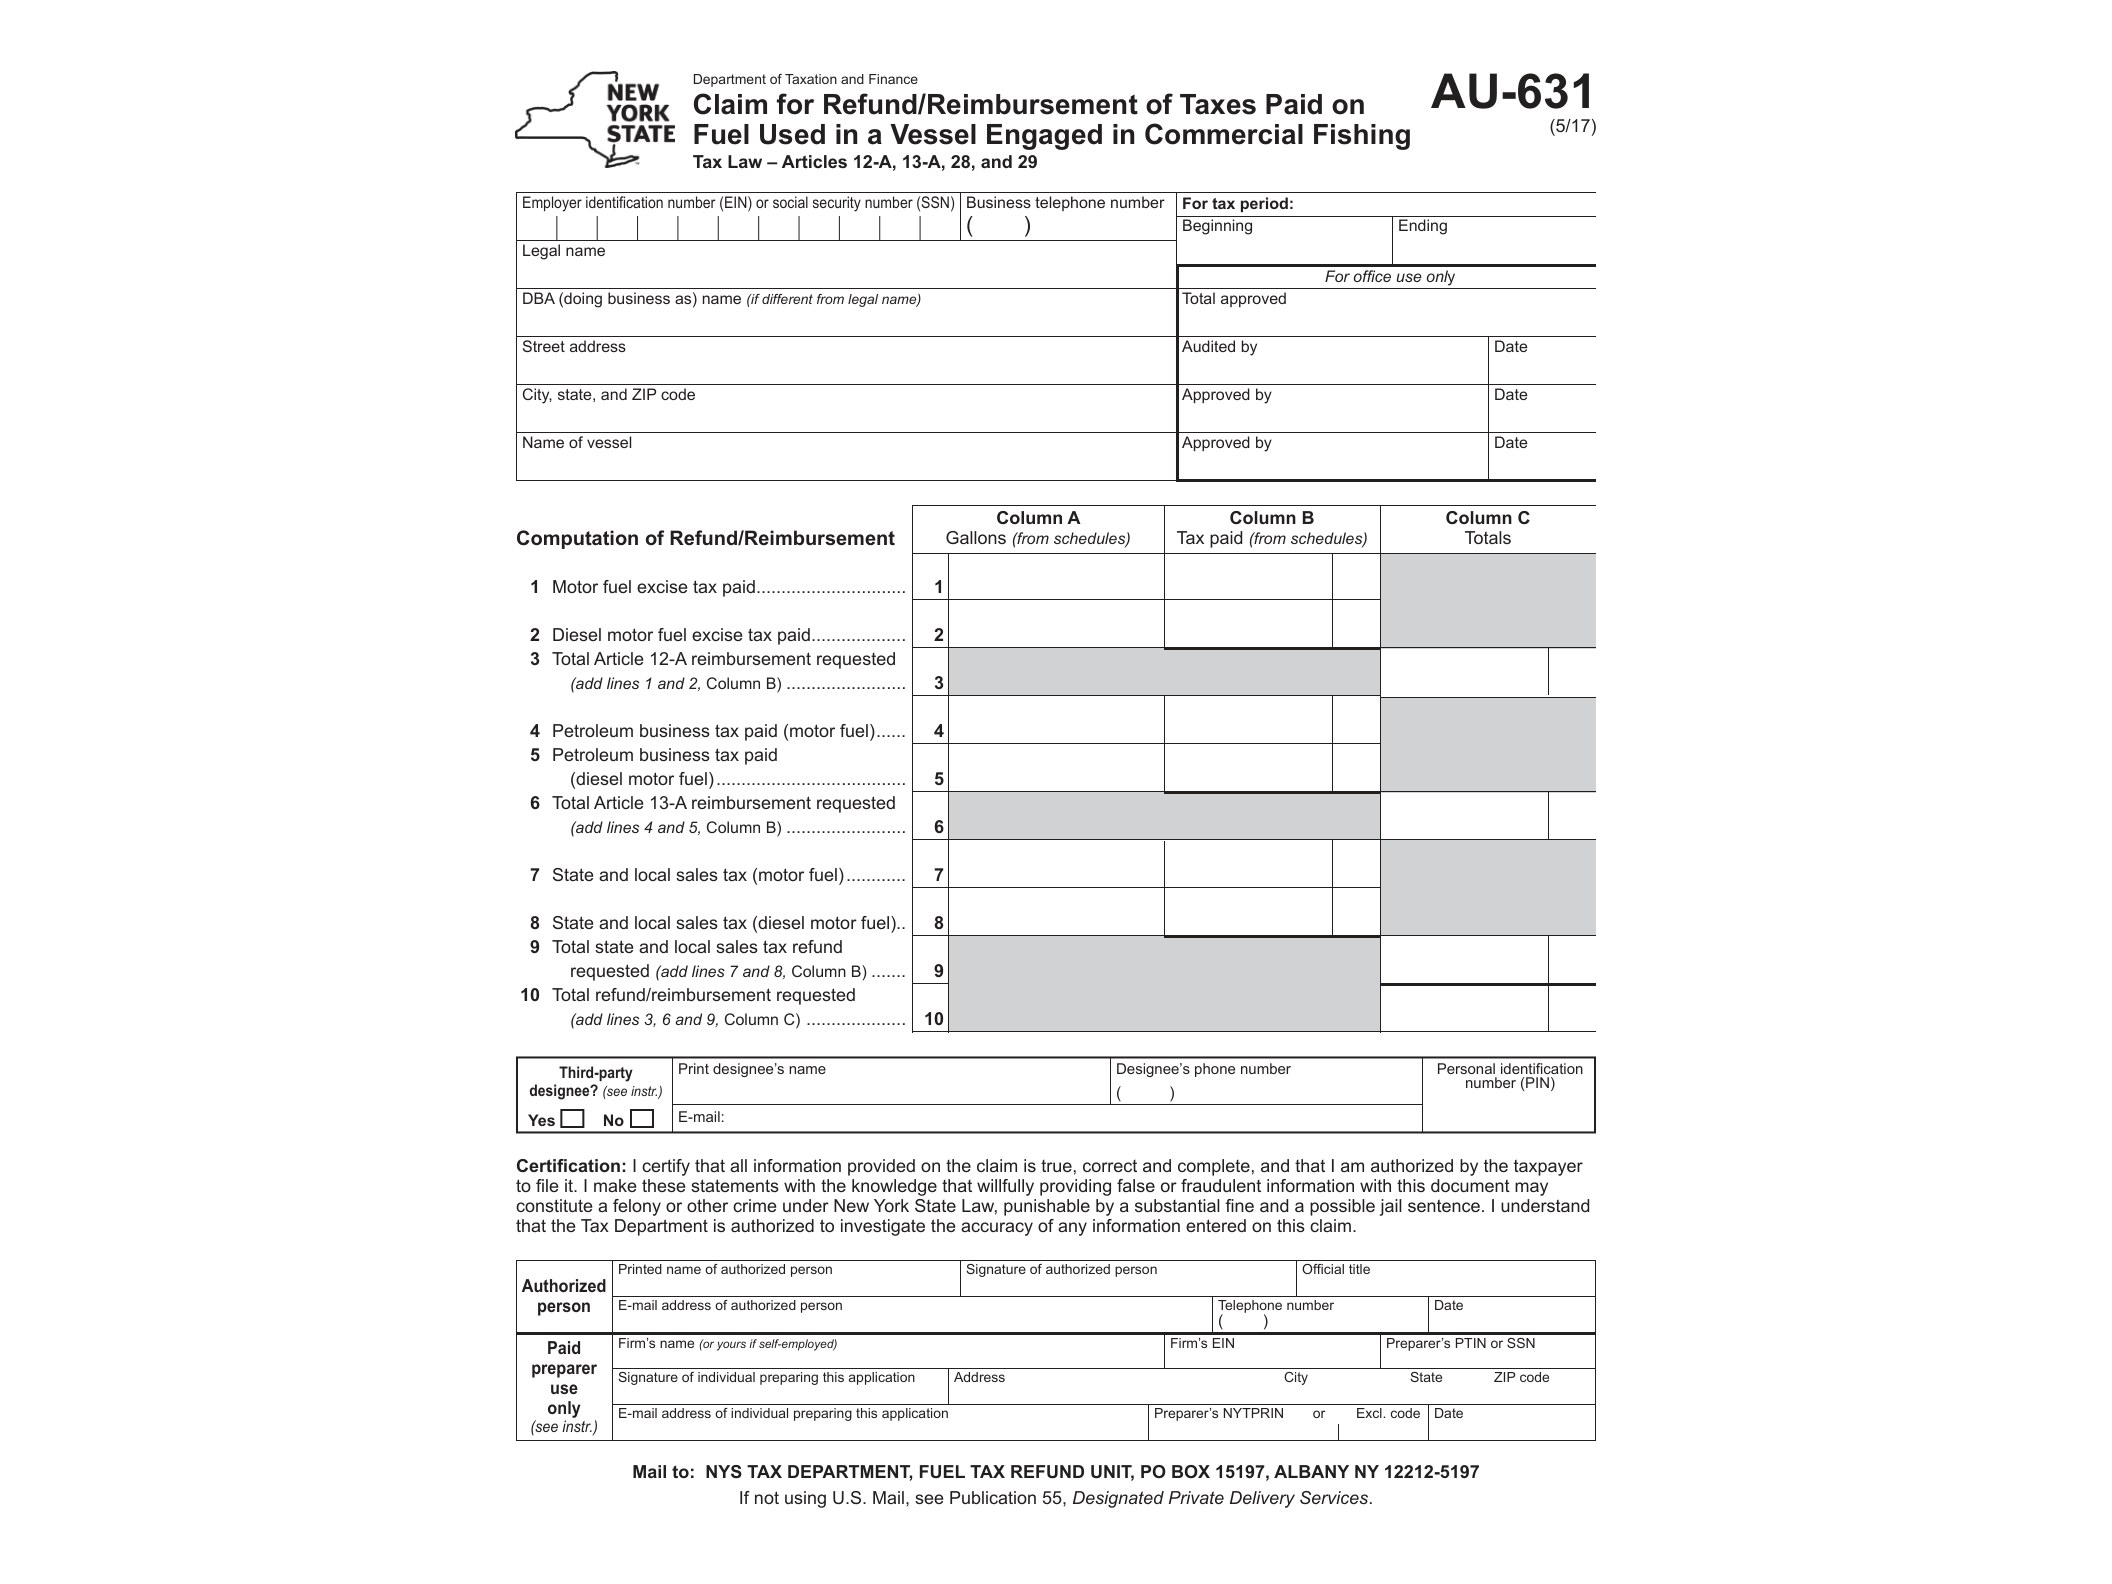
Form AU-631, issued by the New York State Department of Taxation and Finance, lets commercial fishing operators recover fuel taxes they’ve already paid at the pump or point of purchase. If you run a vessel used commercially to catch fish, shellfish, or other seafood for sale, and you bought fuel that included New York State fuel tax, this form is how you get that money back.
The logic behind it is simple: New York doesn’t tax fuel consumed for certain commercial and industrial uses, including fuel burned by vessels engaged in commercial fishing. But most fuel is sold with tax already built into the price, since retailers can’t always know in advance how the fuel will be used. Form AU-631 exists to correct that after the fact, letting eligible fishing businesses claim a refund or reimbursement for taxes they shouldn’t have had to pay in the first place.
Who Should File This Form
This form is meant for owners or operators of vessels used in commercial fishing activity within New York State. That includes fishing boats that purchase diesel, gasoline, or other taxable motor fuel to power the vessel during fishing operations. If your business logs fuel purchases tied directly to commercial fishing trips — not recreational boating, not transport unrelated to fishing — you’re likely eligible to file a claim.
It’s worth noting that this is a fairly narrow use case. It doesn’t apply to general motor fuel purchases for trucks, machinery, or other equipment; those situations are covered under different refund categories, such as Form FT-940, which deals with fuel purchased in volume for certified uses. AU-631 is specific to fuel burned while operating a commercial fishing vessel.
When to Use Form AU-631
You’d file this form after you’ve already paid tax on fuel and can document that the fuel was used for commercial fishing purposes. That means keeping receipts, invoices, or fuel logs that show quantities purchased, dates, and vessel information. The state wants to see a clear paper trail connecting the fuel purchase to the fishing activity before it issues a refund.
There’s typically a filing window tied to the date of purchase, so it’s not something you can put off indefinitely. If you’re claiming a full year’s worth of fuel purchases, it helps to organize your receipts as you go rather than trying to reconstruct everything at tax time.
How to Fill It Out and Submit It
Form AU-631 is not a fillable PDF. You’ll need to print it out and complete it by hand, then mail it in with supporting documentation. Make sure your vessel identification details, business information, and fuel purchase records are accurate and legible, since illegible or incomplete claims tend to get delayed or bounced back for correction.
The form asks for details about the vessel, the fishing business, the fuel type and quantity purchased, and the tax paid on each purchase. Attach copies of your fuel receipts or invoices as proof — the state generally won’t process a refund claim without documentation backing up the numbers you report.
If you’ve dealt with other New York tax refund forms before, the process will feel familiar. It follows a similar structure to forms like Form AU-11, which covers credit or refund claims for sales and use tax, in that you’re documenting a tax already paid and asking the state to return it based on qualifying use. Similarly, businesses that deal with other surcharge refunds, such as those covered under Form AU-100, will recognize the general pattern of proving eligible use to reclaim a tax or surcharge.
Once completed, mail the form along with your documentation to the address listed in the instructions on the form itself. Keep copies of everything you submit, since processing can take time and you may need to reference your submission if the department has questions or requests additional information.
Download Official Form AU631 (PDF)
Opens the official government PDF in a new tab