
Download Official Form RP6704A (PDF)
Opens the official government PDF in a new tab
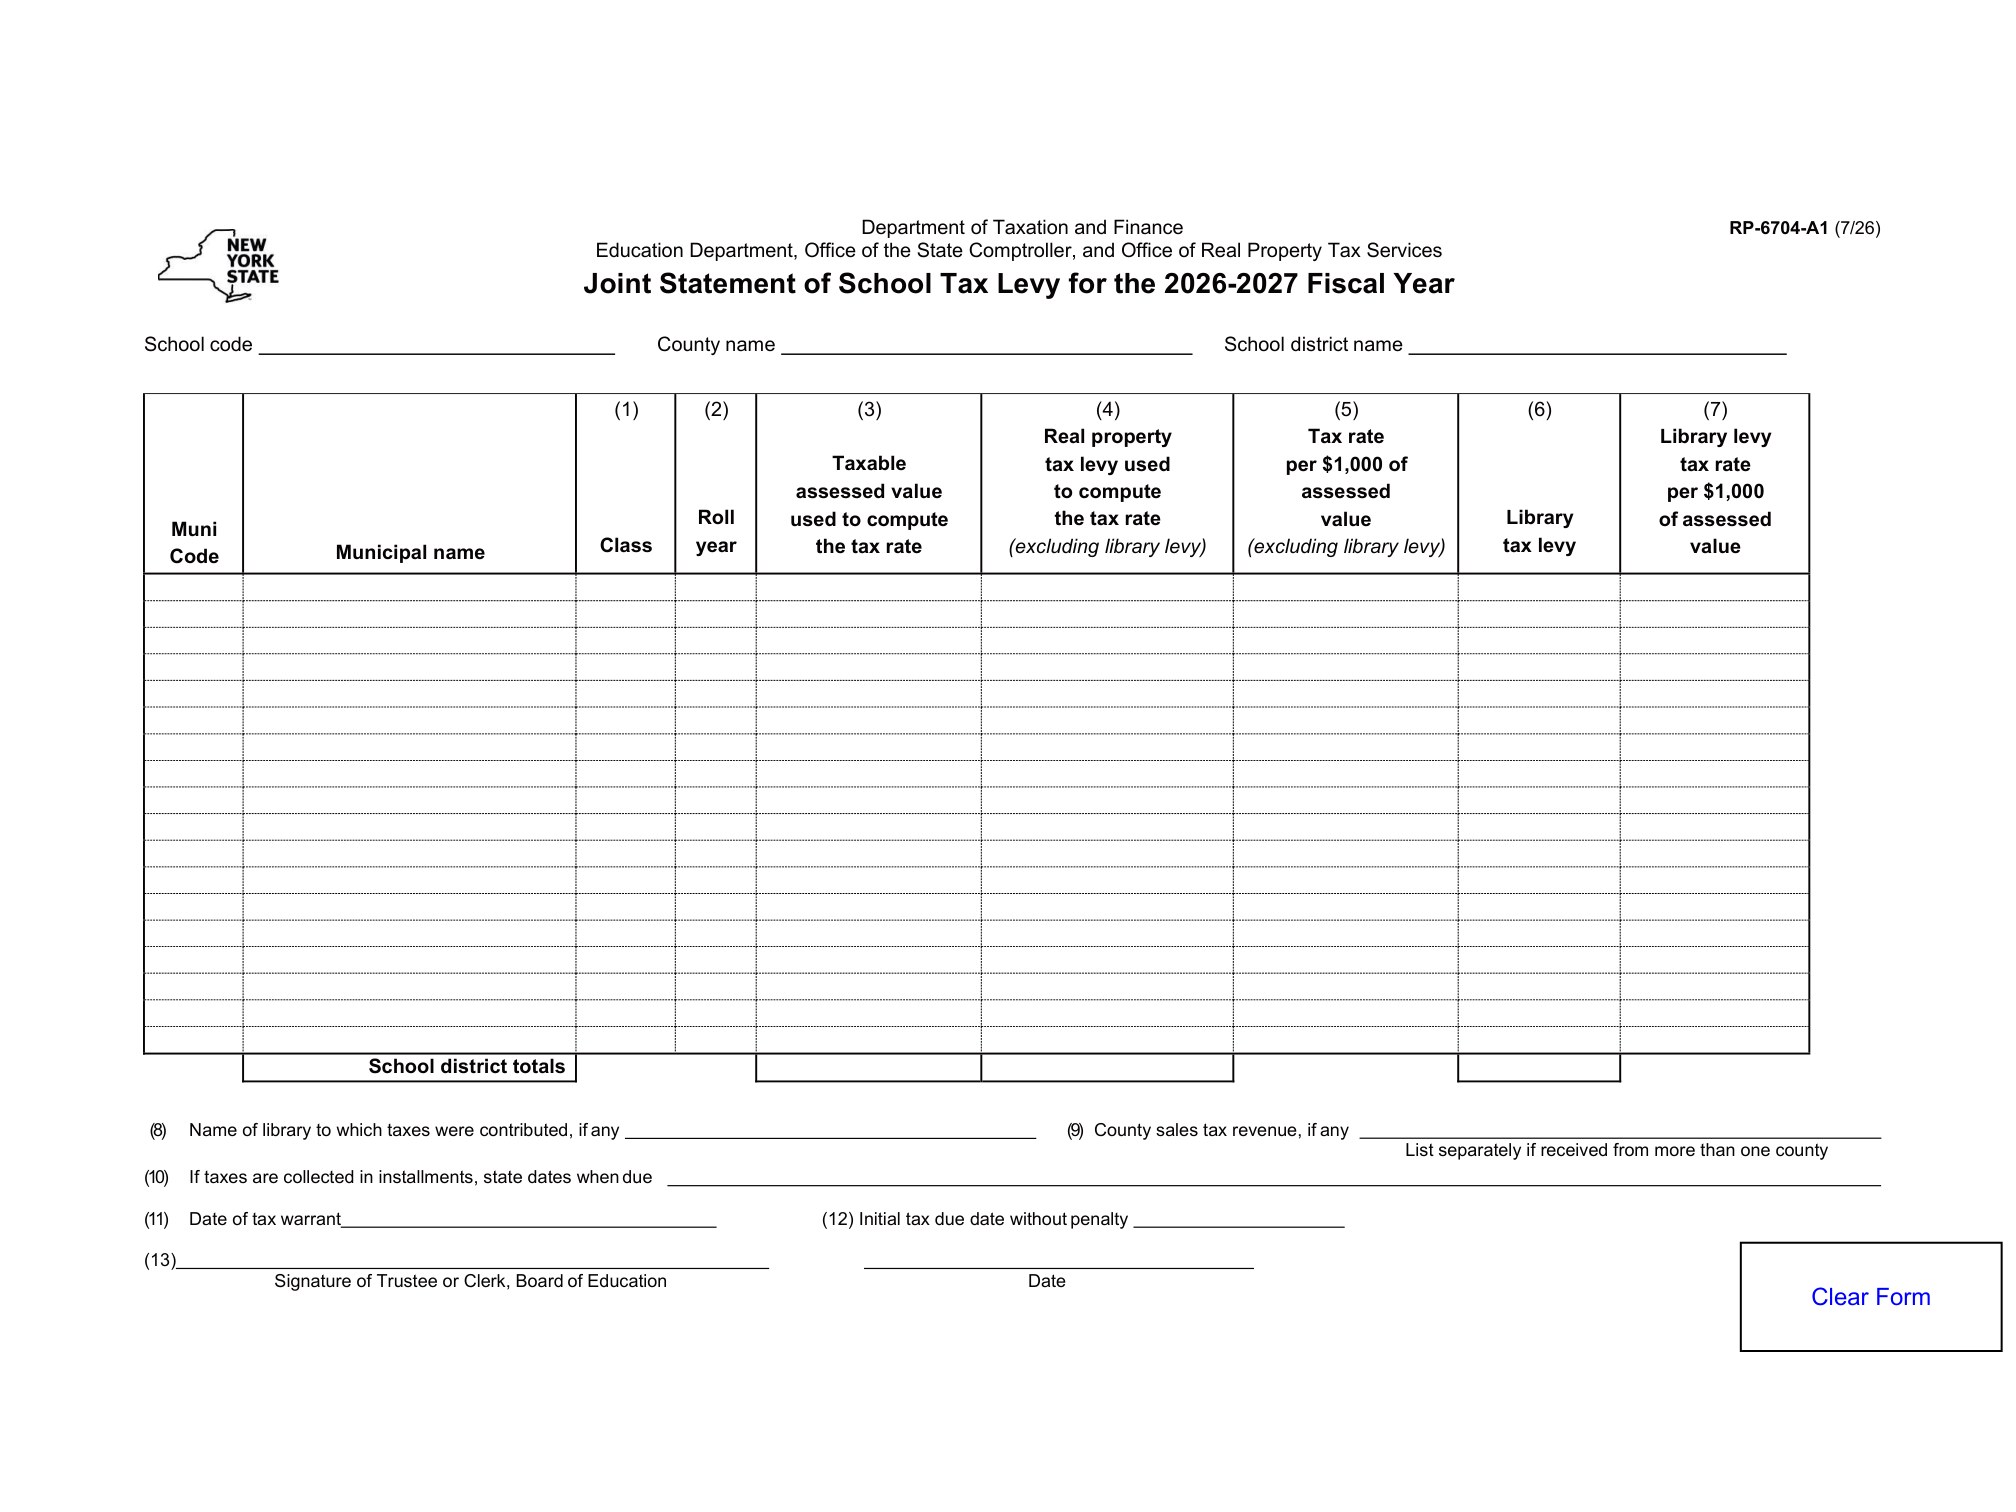
Form RP-6704-A1 is a New York State Department of Taxation and Finance form titled the Joint Statement of School Tax Levy. This specific version applies to the 2024-2025 fiscal year and was revised in July 2025. It’s used by school districts that overlap multiple assessing units, or by assessors and school officials who need to report how a school tax levy is spread across different municipalities within the same district.
School districts in New York frequently cross town, city, or village lines. When a district’s boundaries don’t line up neatly with a single assessing unit, tax officials need a coordinated document showing how the levy is divided and applied. That’s the purpose of this joint statement: it creates a single, agreed-upon record between the relevant taxing jurisdictions so the school tax levy gets calculated and billed accurately across all the affected areas.
Who Needs to File This Form
This isn’t a form that individual homeowners or taxpayers fill out. It’s designed for use by school district officials, town or city assessors, and county real property tax services offices. If you work in one of these roles and your school district spans more than one assessing unit, you’re the intended filer. The form requires cooperation between the different jurisdictions involved, since it’s meant to reflect a joint agreement on how the levy is distributed.
Property owners generally won’t interact with RP-6704-A1 directly, but the numbers it produces eventually show up on their school tax bills. If you’re a homeowner trying to understand why your school tax bill looks a certain way, or if you’re contesting an assessment that affects your share of a school levy, resources like the Notice of Assessor’s Determination of Loss of Property Value explain how assessors document changes that ripple into levy calculations like these.
When This Form Is Used
RP-6704-A1 gets used during the annual school tax levy process, specifically for the 2024-2025 fiscal year in this revision. School districts and assessing units typically complete this statement after the school budget vote and levy amount are finalized, but before tax bills go out. Because school tax calculations depend on equalized values and levy apportionment across jurisdictions, timing matters. Getting the joint statement filed correctly and promptly helps avoid delays or disputes once billing season starts.
If your municipality has been involved in equalization rate disputes, it’s worth understanding how those disputes can affect levy statements. A related process is covered in the Complaint on Tentative State Equalization Rate for Villages, which explains how villages can challenge rates that ultimately factor into levy apportionment across assessing units.
How to Get and Complete the Form
The form is available directly from the New York State Department of Taxation and Finance as a fillable PDF. It has AcroForm fields built in, meaning you can type your entries directly into the document using standard PDF software rather than printing it out and filling it in by hand. This makes it easier for officials from different jurisdictions to prepare, review, and exchange the document electronically before finalizing it.
When filling out RP-6704-A1, you’ll need accurate figures for the total school tax levy, the assessed and equalized values for each portion of the district, and the specific breakdown of how the levy applies to each assessing unit involved. Because this form represents a joint statement, all parties involved in the school district’s overlapping jurisdictions typically need to review and sign off on the figures before it’s submitted.
Double-check the fiscal year designation before submitting, since the state updates this form annually and using an outdated version can create mismatches in reporting. If your work also involves handling taxpayer refund requests tied to school tax corrections, the Application for Refund or Credit of Real Property Taxes is a useful companion form, since levy errors sometimes lead directly to refund claims from affected property owners.
Once completed, the joint statement typically gets filed with the appropriate county real property tax services office and retained by each assessing unit for their records. Keeping copies on file is a good practice in case questions arise later about how a particular year’s school tax levy was apportioned.
Download Official Form RP6704A (PDF)
Opens the official government PDF in a new tab