
Download Official Form AU629 (PDF)
Opens the official government PDF in a new tab
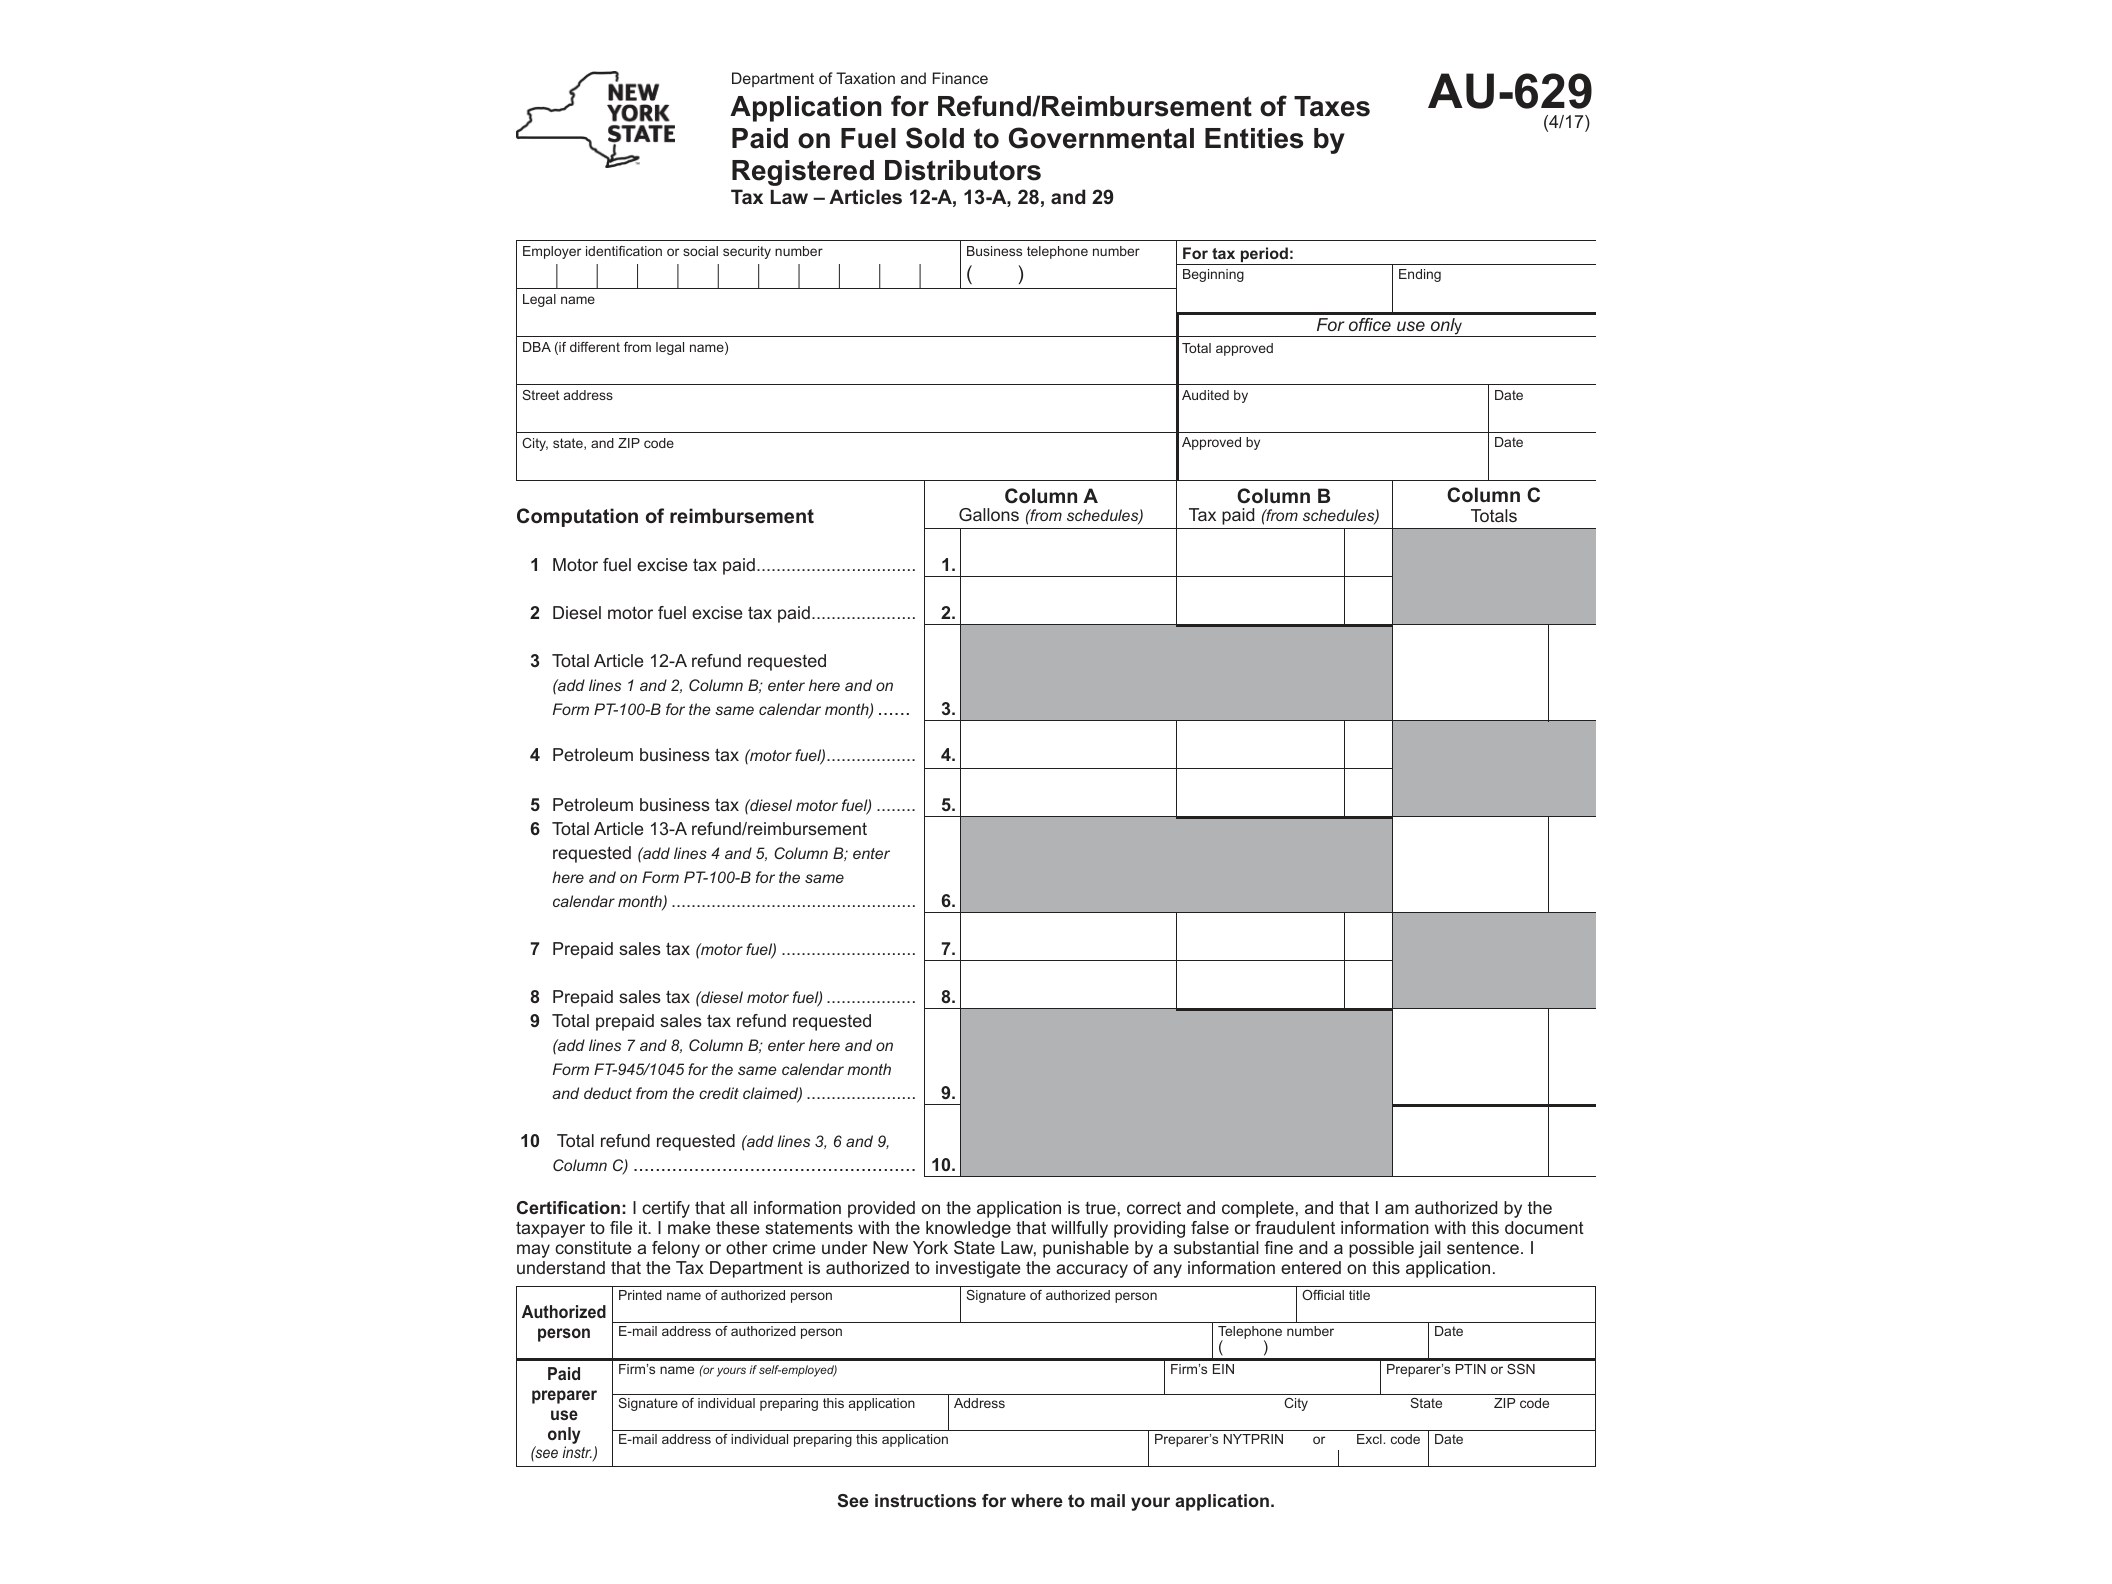
Form AU-619, officially titled Application for Refund/Reimbursement of Taxes Paid on Fuel Sold to Governmental Entities by Registered Distributors, is issued by the New York State Department of Taxation and Finance. It exists for one specific purpose: allowing registered fuel distributors to recover motor fuel or diesel motor fuel excise taxes they already paid to the state when that fuel ends up being sold to a governmental entity that’s exempt from those taxes.
Under New York law, sales of motor fuel and diesel motor fuel to federal, state, and certain local governmental bodies are exempt from excise tax. The problem is that distributors typically pay the tax upfront when they bring fuel into the state or purchase it from another registered distributor. When that same fuel later gets sold to a tax-exempt governmental buyer, the distributor has effectively overpaid. Form AU-619 is the mechanism for getting that money back.
Who Needs to File AU-619
This form is strictly for registered distributors of motor fuel or diesel motor fuel in New York State — not retail consumers, not government agencies themselves, and not unregistered resellers. If you’re a registered distributor who sold fuel to a qualifying governmental entity (such as a city, county, school district, or a federal agency) and you already paid the applicable excise tax on that fuel earlier in the supply chain, you’re the one entitled to file for reimbursement.
It’s worth noting the distinction here: the government buyer doesn’t pay the tax and doesn’t file this form. Instead, the distributor who absorbed the tax cost upstream is the party seeking the refund, since they’re the one who remitted the tax to the state in the first place.
When to Use This Form
You’d use Form AU-619 after completing a sale of tax-paid fuel to a governmental entity. Because refund claims are time-sensitive under New York’s tax code, distributors should file as soon as the relevant sales records and supporting documentation are ready, rather than letting claims pile up. Each claim period generally corresponds to sales made during a specific timeframe, so distributors handling frequent government fuel sales often submit this form on a recurring basis as part of their regular tax compliance routine.
Distributors who deal with mixed sales — some taxable, some exempt — need to keep especially careful records, since the refund is only valid for the portion of fuel that was demonstrably sold to an exempt governmental buyer. Sloppy recordkeeping is the most common reason these claims get delayed or rejected.
How to Get and Complete the Form
Form AU-619 is a static PDF — it is not a fillable digital form. That means you’ll need to download it, print it out, and complete it by hand using black ink, following the same care you’d apply to any other state tax filing. Given how precise fuel tax calculations tend to be, it’s a good idea to double-check gallon totals, tax rates, and sale dates before submitting, since errors can trigger a request for additional documentation or an outright denial.
The form asks for identifying information about the distributor, details of the governmental entity that purchased the fuel, the volume and type of fuel sold, and the amount of tax originally paid that’s now being claimed for refund. Supporting invoices or delivery records showing the exempt sale should be kept on hand, since the Department of Taxation and Finance may request them to verify the claim.
Distributors who regularly manage other New York tax filings — such as those working with computer-generated CT-2658 and IT-2658 forms, or handling mortgage recording tax returns — will recognize the same pattern here: New York expects precise, well-documented paperwork before releasing any refund. If your business also deals with reportable transaction disclosures, it’s worth reviewing the instructions for Form DTF-686 as part of your broader compliance checklist, since New York tends to apply similarly strict documentation standards across its tax programs.
Once completed, the form should be mailed to the address specified in the form’s instructions, along with any required attachments. Keep a copy of everything submitted, since fuel tax refund claims can sometimes take several weeks to process and having your own records on hand makes it easier to respond to any follow-up questions from the Department.
Download Official Form AU629 (PDF)
Opens the official government PDF in a new tab