
Download Official Form AU432 (PDF)
Opens the official government PDF in a new tab
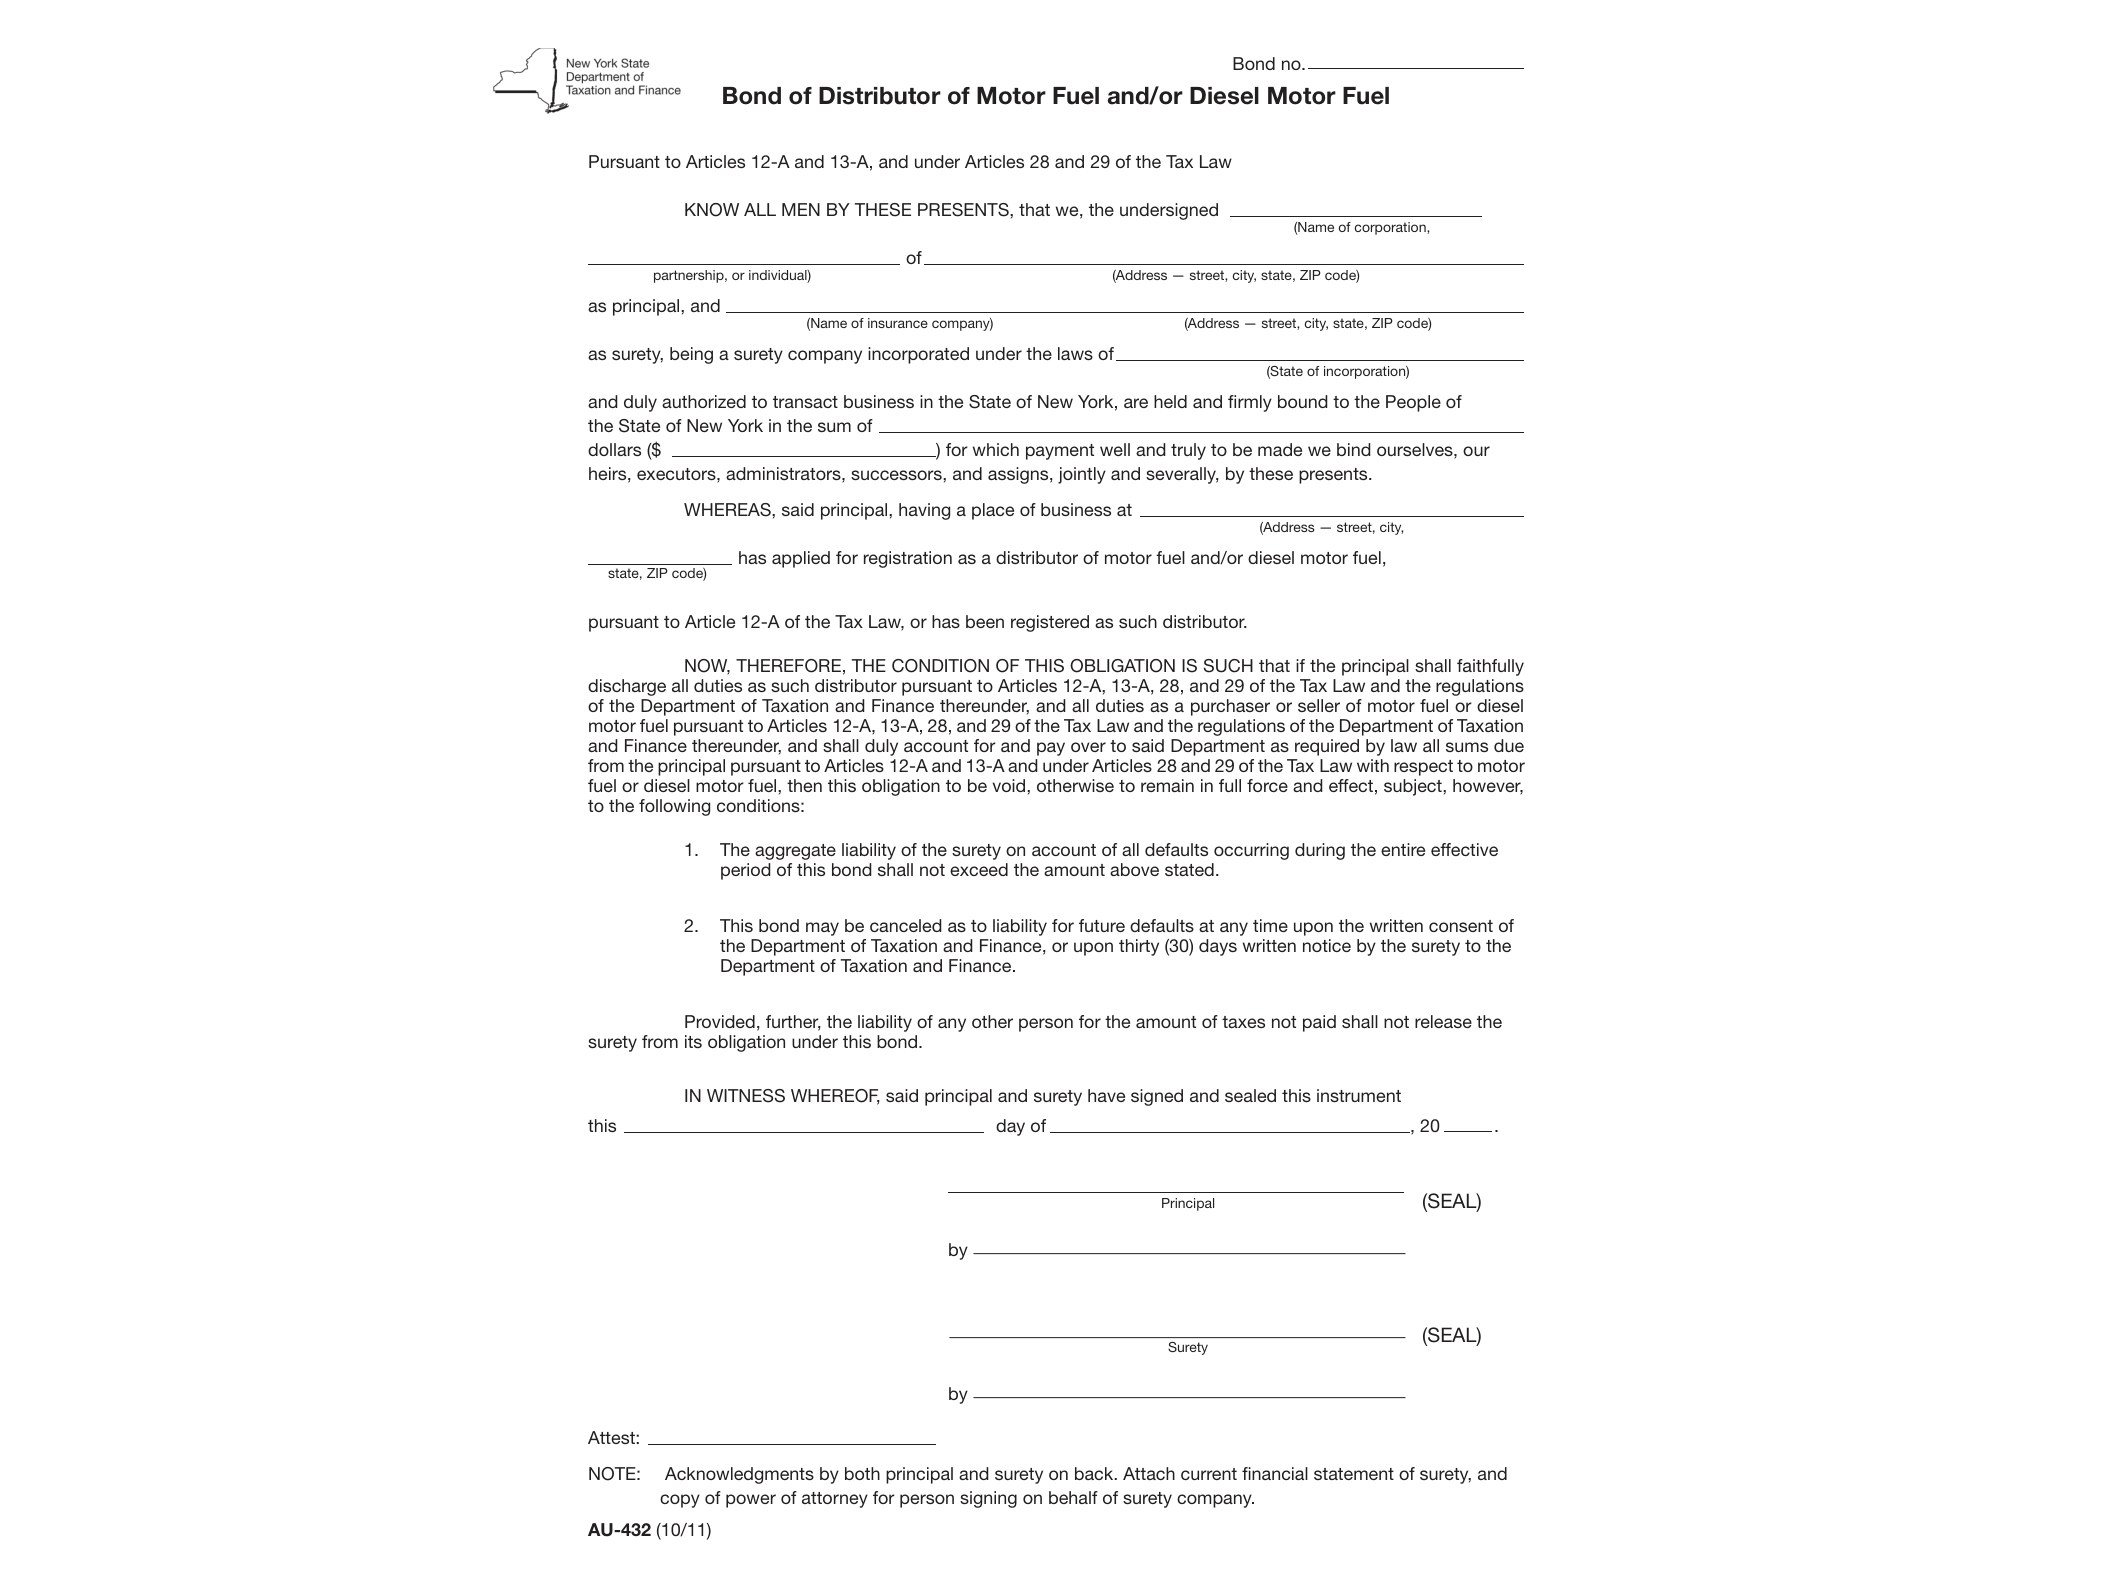
Form AU-432, issued by the New York State Department of Taxation and Finance, is a surety bond agreement required from businesses licensed to distribute motor fuel and/or diesel motor fuel in New York State. It’s not a tax return or a claim form — it’s a financial guarantee that protects the state in case a distributor fails to pay the fuel taxes it collects and owes.
If you’re registering as a distributor of motor fuel or diesel motor fuel under New York’s Tax Law, the Department of Taxation and Finance can require you to post a bond before issuing or renewing your distributor license. Form AU-432 is the standard document used to establish that bond. It names the distributor as the principal, a surety company (typically an insurance company licensed to write surety bonds in New York) as the guarantor, and the New York State Commissioner of Taxation and Finance as the obligee, or the party protected by the bond.
Who Needs Form AU-432
This form applies specifically to businesses that hold or are applying for a distributor of motor fuel license, a distributor of diesel motor fuel license, or both, in New York. Distributors are the companies that import, produce, or otherwise first handle motor fuel and diesel motor fuel in the state’s distribution chain, and they’re responsible for collecting and remitting excise taxes on those products.
Not every distributor is automatically required to post a bond. The Department typically requires one when a business is new to fuel distribution, has a history of late payments or tax delinquency, or otherwise poses a higher risk of non-payment. If the Department notifies you that a bond is required as a condition of licensing, Form AU-432 is the document your surety company will complete and submit on your behalf.
When This Bond Comes Into Play
The bond guarantees payment of motor fuel and diesel motor fuel taxes, along with any penalties and interest that might accrue if the distributor doesn’t pay what it owes. If a licensed distributor defaults on its tax obligations, the state can make a claim against the bond up to the bond’s face amount to recover the unpaid taxes. This protects New York’s tax revenue without the state having to chase every distributor through separate collection actions before it can recoup losses.
The bond amount itself is set by the Department of Taxation and Finance based on factors like the distributor’s expected volume of fuel sales and its tax liability history. Once approved, the bond generally stays in effect until the distributor’s license is terminated, the bond is canceled by the surety with proper notice, or the Department releases the obligation.
How to Get and Complete Form AU-432
Because AU-432 is a legal bond instrument, it’s not something you fill out casually on your own. Distributors typically work through a licensed surety or insurance company that specializes in tax bonds. The surety company completes the form with the distributor’s business information, the bond amount set by the Department, and the surety’s own identifying details, then both the distributor and an authorized representative of the surety sign it.
The form is not fillable digitally — you’ll need to download the PDF, print it, and complete it by hand or have your surety provider prepare it and print a signed copy. Once fully executed, the bond is submitted to the New York State Department of Taxation and Finance as part of the distributor licensing or renewal package.
If your business also deals with fuel tax refunds, it’s worth reviewing Form AU-619 for fuel tax refunds on sales to government entities, since distributors sometimes handle both bonding requirements and refund claims in the same operational cycle. Businesses juggling multiple New York tax filings may also find it useful to check requirements around computer-generated tax forms standards if they’re preparing other state filings in-house, and larger fuel distribution companies dealing with complex reporting obligations should keep an eye on related guidance such as the instructions for tax shelter reportable transactions, which can affect how certain fuel-related business structures are reported.
Keep a copy of the executed bond for your own business records, and confirm with the Department of Taxation and Finance that the bond amount matches what was required for your specific license application or renewal before submitting it.
Download Official Form AU432 (PDF)
Opens the official government PDF in a new tab